Social Responsibility Driven Financial Intermediation
Innovative and technological pathways to maqasid-aligned transformations
Use the arrows, ← → keys or swipe to turn pages
Cambridge Global Islamic Finance Report
GIFR 2026
Social Responsibility Driven Financial Intermediation
Innovative and Technological Pathways to Maqasid-aligned Transformations
Published by
Strategic Partner
Knowledge Partner
Cambridge Global Islamic Finance Report
GIFR 2026
Published by
Produced by
GIFR is the official publication of Cambridge Institute of Islamic Finance and is produced by Cambridge IFA.
About Cambridge Institute of Islamic Finance
Cambridge Institute of Islamic Finance – Cambridge-IIF – is an independent research centre, specialising in the financial sectors of the countries wherein Islamic banking and finance is a significant activity. Leveraging upon the academic resources the city of Cambridge has to offer, Cambridge-IIF is well-positioned to undertake research projects to study the global phenomenon of Islamic banking and finance. Cambridge-IIF aims at conducting policy-oriented research to further spur growth in Islamic banking and finance, with a special focus on the Sustainable Development Goals (SDGs).
About Cambridge IFA
Cambridge IFA is a financial services intelligence house that specialises in developing and utilising powerful cutting-edge analytical tools to evaluate business data, assess macroeconomic indicators and understand market trends, leadership positioning and brand development relevant to the development of the financial services industry globally. For more information visit www.cambridge-ifa.net
Please cite this report as: Cambridge Institute of Islamic Finance (2026). Global Islamic Finance Report 2026. London: United Kingdom.
Acknowledgements
We are thankful to all the organisations and institutions that have supported this industry-building initiative of immense importance. Being the first global annual report on Islamic banking and finance, GIFR has played a pioneering role in providing Islamic financial intelligence to all the stakeholders in the industry. The following institutions deserve special appreciation for contributing to the success of this venture. Without their support, it would have been difficult for us to bring this edition of GIFR.
Strategic Partner
Knowledge Partner
Founder & Editor-In-ChiefDr Humayon Dar
International Advisory BoardChairmanShahid MalikFormer International Development Minister, UKMembersSheikh Nedham Yaqubi - Shari’a ScholarDr Mian Farooq Haq - State Bank of PakistanDato’ Dr Asyraf Wajdi Dusuki - Islamic Finance ExpertDr Rizwan Malik - Bahrain Insititute of Banking and FinanceMufti Talha Azami - Shari’a ScholarSohail Jaffer - Capita Middle EastMuhammad Saleem Ahmed Ranjha - Wan Miana Rural Development Programme
Senior EditorSara Ahmad
Associate EditorsKanwal Javed & Ramsha Mughal
Assistant EditorEman Fatima
Senior Visual DesignerKhalil Ahmed
Junior DesignerZeeshan Yousaf
Websitehttps://gifr.cambridge-ifa.net
PublisherCambridge Institute of Islamic FinanceEmail: [email protected]
Advertisements, Commercial and Subscription EnquiriesEmail: [email protected]
Disclaimer
All rights reserved. No part of this publication may be reproduced, stored in a retrieval system, or transmitted, in any form, or by any means electronic, mechanical, photocopying, recording or otherwise, without the prior permission of the author concerned and/or Cambridge Institute of Islamic Finance, except by a reviewer who may quote brief passages in publishing review. The opinions and positions expressed by the authors of this publication are not necessarily the opinions of Cambridge Institute of Islamic Finance, the co-editors or sponsors. None of the above individuals or organisations necessarily endorses any of the methods or conclusions contained herein. Readers of this publication should independently verify any information through competent legal, tax, accounting, banking and other experts of their choice. Publisher will not be responsible for any errors, omissions or misrepresentation, if there are any.
Dr Hussain Mohi-ud-Din Qadri, Deputy Chairman, Board of Governors, Minhaj University Lahore23
Table of Acronyms24
Part 1: Global Islamic Financial Services Industry
Chapter 1:Overview of the Global Islamic Financial Services Industry29
Chapter 2:Islamic Finance Country Index – IFCI 202643
Part 2: Circular Economy based Alternatives to the Current Forms of Financial Intermediation
Chapter 4:Circular Economy-based Alternative Models to the Currently Adopted Forms - An Overview69
Part 3: Waqf-based and Sustainability-aligned Model for Financial Intermediation
Chapter 7:Waqf-based Sustainability Through Malaysia Social Exchange (Impakrintas)99
Chapter 8:Operational Frameworks and Institutionalisation of Sustainability-aligned Waqf Models113
Chapter 9:Legal and Regulatory Foundations for Waqf-based Financial Intermediation121
Part 4: Commodity-based Alternatives to the Current Forms of Financial Intermediation
Chapter 10:A Study of Commodity-based Alternatives to the Current Forms of Financial Intermediation137
Part 5: Technological and Innovative Alternatives to the Current Forms of Financial Intermediation
Chapter 12:Impact of Next Gen AI-driven FinTech on the Current Forms of Financial Intermediation169
Chapter 13:A View from the Engine Room of Islamic Financial Technology – Case Study of Nigeria195
Chapter 14:The Elephant of Debt and the Promise of Islamisation203
Index of Terms and Bibliography301
EditorialTeam
Sara Ahmad
Senior Editor Cambridge-IFA
Sara Ahmad is the lead editor at Cambridge-IFA. She has served in the domains of Information Technology, Health Technology and Islamic Finance. Experienced in collaborating with several multilateral agencies, she joined Cambridge-IFA, a global Islamic finance advocacy platform, transitioning from Health Information Technology to Islamic Banking and Finance with the aim of documenting and catalysing the industry’s progress in this era of transformative change. She completed her post-graduation in Information Technology from National University of Science and Technology (NUST), Pakistan.
Kanwal Javed
Associate Editor Cambridge IFA
Kanwal Javed is an Associate Editor at Cambridge IFA, with an academic background in English Language and Literature and experience in editing, proofreading, and reviewing professional publications. Her expertise includes language, style, structure, and editorial consistency, helping authors communicate their ideas with clarity, precision, and impact while preserving their individual voice. She ensures that content is grammatically accurate, stylistically coherent, and well-structured. Through her work at Cambridge IFA, she contributes to maintaining high editorial standards and developing polished, engaging, and high-quality publications.
Ramsha Mughal
Associate Editor Cambridge IFA
Ramsha Mughal is an Islamic banking and finance enthusiast and Associate Editor at Cambridge IFA, where she contributes to editorial excellence through proofreading, writing short articles and ensuring content coherence. She holds an MS in Islamic Banking and Finance from the International Islamic University Islamabad, Pakistan. Her experience in the Islamic Microfinance Division of a microfinance bank gave her practical exposure to Islamic financing and product utilisation. She aspires to become an Islamic finance specialist and contribute meaningfully to the industry’s growth.
Eman Fatima Rana
Associate Editor Cambridge IFA
Eman Fatima Rana is an Associate Editor at Cambridge IFA with a strong academic background in English and linguistics. A gold medalist in English, she holds an MPhil in Linguistics from Bahauddin Zakariya University. As an avid reader, she credits her love for reading as the foundation for her strong editorial eye. At Cambridge IFA, she ensures complex Islamic finance concepts are communicated clearly and accurately, using her linguistic expertise. She helps authors present ideas with precision while preserving their voice, contributing to high-quality publications.
The fundamental question for the next fifty years of Islamic finance is no longer simply: what problems are we trying to solve? The original ambition, to create a parallel financial industry that provides Muslims with Shari'a-compliant alternatives to conventional finance, was necessary and transformative. Yet, as Islamic finance has matured into a substantial global industry, compliance alone is no longer sufficient as its defining ambition. The next phase requires a deeper transition: from compliance to consciousness. Islamic finance must increasingly ask not only whether a financial transaction is permissible, but whether it contributes to human wellbeing, economic justice, shared prosperity and the responsible stewardship of resources.
At the heart of this transformation lies the concept of Capital as Amana: capital not merely as an instrument of accumulation, but as a trust carrying responsibilities towards people, society and future generations. This perspective can help reposition finance from an extractive mechanism towards a force for productive, inclusive
and sustainable economic activity. The ultimate ambition is therefore a credible solution for humanity: helping repair an economy weakened by excessive debt, inequality, short-termism and declining trust. The next fifty years should move Islamic finance beyond building a successful industry towards building economies with a heart, economies in which finance serves human flourishing and the common good.
The pioneers who had a role in the revitalisation of the industry during the past fifty years dedicated efforts with conviction to transform a moral aspiration into an institutional reality. Their task was both practical and historic: to mobilise faith-sensitive savings and channel them into trade, investment and infrastructure while demonstrating that financial activity could operate within an ethical and Shari'a-based framework. In doing so, they established the foundations of Shari'a governance, standards, legal precedent, scholarship and professional capability. Islamic finance also helped bring millions of people into formal financial systems and, across several post-colonial economies, contributed to the development of greater financial sovereignty and locally rooted financial institutions. Among those who shaped this formative journey were Sheikh Saeed Lootah, Sheikh Saleh Kamel, Prince Mohammed Al Faisal, Dr Ahmad Mohamed Ali Al-Madani and Royal Professor Ungku Aziz, alongside many other scholars, entrepreneurs, policymakers, bankers and institution-builders. Their collective contribution extended far beyond establishing banks. They created markets, regulatory frameworks, standards, intellectual traditions and human
The Next Fifty Years of Islamic Finance - From Compliance to Consciousness, Capital as Amana, Economies of the Heart | Chapter 3
Global Islamic Finance Report 2026 | 65–68
capital that enabled Islamic finance to evolve into a global industry. The pioneers built a bridge. Our generation must now decide where that bridge should lead. The achievement of the first fifty years was to prove that Islamic finance could exist, grow and institutionalise itself. The challenge of the next fifty is to determine how that institutional foundation can serve a wider human purpose.
The first fifty years proved that Islamic finance could exist, grow and institutionalise itself. The challenge of the next fifty is to determine how that institutional foundation can serve a wider human purpose.
The Islamic finance industry today represents an extraordinary achievement in institutional development, global reach and financial innovation. From its relatively modest beginnings, it has evolved into a global ecosystem with US$5.78 trillion in Islamic finance assets in 2025, reflecting 21 per cent year-on-year growth, with a presence extending across 140 countries and supported by more than 1,500 Islamic financial institutions worldwide . These figures represent more than scale: they demonstrate the ability of an idea rooted in faith, ethics and responsible finance to develop into a significant component of the international financial system.
Over five decades, Islamic banking, sukuk, takaful, Islamic investment and social finance have created institutions, markets,
Chapter 3 | The Next Fifty Years of Islamic Finance - From Compliance to Consciousness, Capital as Amana, Economies of the Heart
68 | Global Islamic Finance Report 2026
standards, professional capabilities and regulatory frameworks that reach far beyond the countries in which the industry first emerged. Yet these achievements also invite a more fundamental question about the next stage of its evolution. Scale is no longer the question. Purpose is. The challenge ahead is not simply to increase assets, institutions or market share, but to consider what this considerable financial capacity should ultimately accomplish. Can the industry translate its principles into broader economic and social value, strengthening inclusion, trust, sustainability, shared prosperity and human wellbeing? The next fifty years therefore require Islamic finance to move from demonstrating that it can grow to demonstrating what its growth can meaningfully achieve.
InspirationalDissatisfaction
The critique of the current Islamic financial industry is fair. Too much of Islamic finance has been characterised by replication, debt-like structuring and an excessive emphasis on legal form, while too little attention has been given to genuine risk-sharing, measurable impact and the wider social imagination that the discipline can inspire. Yet the critique should not become a verdict. Islamic finance grew out of post-colonial economies in which the immediate priorities were to mobilise savings, broaden financial inclusion, establish institutional legitimacy and build credibility within financial systems largely designed around conventional models. In that context, gradualism was not only understandable; it was often necessary. The bridge that Islamic finance built between principle and practice served a vital purpose. But a bridge is a means of transition, not the destination. There is a useful precedent outside our tradition. John C Bogle built Vanguard and then spent
The Next Fifty Years of Islamic Finance - From Compliance to Consciousness, Capital as Amana, Economies of the Heart | Chapter 3
Global Islamic Finance Report 2026 | 68–69
much of his later life as his own industry's most loving and persistent critic. His dissatisfaction was not destructive; it was disciplined, constructive and ultimately transformative, helping give the world its first index fund. Islamic finance now needs a similar spirit of insider dissatisfaction. We must ask not only, “Is this transaction permitted?” but also: What does it make possible? Who benefits? Who carries the risk? What remains after the return is distributed?
TheOperatingPrinciple:CapitalasAmana
These questions need to be considered in the light of the Qur'an: “We offered the Trust to the heavens, the earth and the mountains... yet humanity accepted it” (Qur'an 33:72). The verse highlights the importance of trust as an operating principle. To develop a morally aligned financial system, the operating principle must be Capital as Amana: a trust, not a possession. This profound verse reminds us that capital is not something we own absolutely, but something we hold in trust. Amana asks three questions of capital: How was it earned? How is it deployed? Who bears the consequences? These questions create three corresponding trusts. First, to Allah (SWT): justice, transparency, no riba or gharar, and a genuine sharing of risk and reward. Second, to community: households, entrepreneurs, workers, and those still excluded from opportunity.
Third, to the future generations who will inherit the institutions, environment and the social fabric that our capital creates. Compliance is the minimum possible requirement of this transformation and it is not an end in itself. Consciousness elevates financial principles beyond mere legal form and carries the purpose of Shari'a into every allocation decision in the service of the whole of humanity. This principle, Capital as Amana, challenges us to move
Chapter 3 | The Next Fifty Years of Islamic Finance - From Compliance to Consciousness, Capital as Amana, Economies of the Heart
69 | Global Islamic Finance Report 2026
beyond minimal legal compliance towards a deeper ethical consciousness that animates every financial decision
Global public debt stands at a record US$102 trillion, while developing countries paid a record US$921 billion in interest in a single year, and 3.4 billion people now live in countries that spend more on interest payments than on health or education
ADifferentMoralArchitecturefortheGlobalEconomy
The prevailing financial system persists without a soul, reducing many of the world's economies to debt-ridden architectures. The urgent need today is for a different moral architecture underpinning the financial system. Consider the current state: global public debt stands at a record US$102 trillion, while developing countries paid a record US$921 billion in interest in a single year, and 3.4 billion people now live in countries that spend more on interest payments than on health or education. Global growth is projected at just 2.5 per cent in 2026, the slowest pace since the pandemic. Owners' capitalism has mutated into managers' capitalism, where agents are rewarded ahead of the owners they serve; a phenomenon that John C Bogle warned about extensively.
The Next Fifty Years of Islamic Finance - From Compliance to Consciousness, Capital as Amana, Economies of the Heart | Chapter 3
Global Islamic Finance Report 2026 | 69
We see leverage and quarterly extraction, where gains are privatised and losses socialised. Zero-sum fragmentation prevails just when climate, food and health demand cooperation. In contrast, the Islamic architecture offers a compelling alternative. It offers capital connected to real assets and productive enterprise, risk shared and not transferred to the weakest party, returns earned with responsibility, wealth circulated and not merely accumulated, and finance judged by its contribution to adl, ihsan and human dignity. We are not swapping one label for another. Instead, we are building role-model institutions and economies whose outcomes speak for themselves. Our task is to help give capitalism back its moral compass, drawing on Islamic principles that have always emphasised justice, risk-sharing and the circulation of wealth.
TwoWitnessesfromtheHeartofCapitalism
Two witnesses from the heart of capitalism itself, Adam Smith and John C Bogle, offer powerful testimony to the moral foundations we seek to restore. Adam Smith, in The Theory of Moral Sentiments (1759), written seventeen years before The Wealth of Nations, argued that markets rest on moral sentiments. Justice is the main pillar of society and beneficence its ornament: “the prevalence of injustice must utterly destroy it” Conscience is “the man within the breast”, the impartial spectator who judges us when no auditor is watching. Smith warned of the corruption of our moral sentiments that flows from admiring the rich and neglecting the poor. John C Bogle, founder of Vanguard and author of The Battle for the Soul of Capitalism (2005), was one of capitalism's most insightful critics from within.
Bogle argues managers’ self-interest in running a business has
Chapter 3 | The Next Fifty Years of Islamic Finance - From Compliance to Consciousness, Capital as Amana, Economies of the Heart
69–70 | Global Islamic Finance Report 2026
outpaced owners’ capitalism, becoming managers’ capitalism. Speculation has crowded out investment: short-term price over long-term value. The more the financial system takes, the less the investor keeps, and the costs decide outcomes. Bogle's remedy was fiduciary duty, stewardship over salesmanship, and the restoration of trust. These two witnesses remind us that capitalism's own conscience aligns with Islamic values. These ethical values, which on one hand pervade Islamic teachings, are on the other hand needed to kindle the conscience of conventional financial systems.
TheRoleoftheState:Referee,UmpireandPartner
Markets supply the energy of an economy, but the state supplies the rules of the game and the confidence to play it. The role of the state must be understood in three dimensions: referee, umpire and partner. As referee, the state sets and enforces just rules, drawing on Smith's second duty of the state: “an exact administration of justice”. As umpire, it remains impartial between all players, protecting the weaker party and adjudicating without fear or favour, with standards applied consistently to state and private actors alike. Our hisba tradition teaches that market oversight is a public trust. As allocator and partner, the state funds what markets under-supply, in the tradition of Smith's public works and the Bayt al-Mal, providing catalytic guarantees, anchor capital and sovereign sukuk for real infrastructure. It crowds private capital in, never out.
This threefold role creates a level playing field for risk-sharing finance, with tax and regulatory neutrality. A state that referees fairly, umpires impartially and allocates catalytically in genuine partnership with the private sector is fundamental to capitalism with a moral core. The state must not substitute for markets but must
The Next Fifty Years of Islamic Finance - From Compliance to Consciousness, Capital as Amana, Economies of the Heart | Chapter 3
Global Islamic Finance Report 2026 | 70
create the conditions for them to serve the common good.
The next fifty years of Islamic finance call for a fundamental transformation in the way capital, institutions and economic development are understood. Five shifts can be envisaged as the building blocks of a framework for a more purposeful, innovative and inclusive financial system. The first shift, from form to purpose, encourages institutions to look beyond contractual compliance and measure their contribution to society through employment, education, healthcare, housing and other meaningful outcomes. The second shift, from replication to innovation, highlights the importance of developing business models and digital solutions that respond to contemporary needs rather than merely reproducing existing financial products. The third shift, from debt bias to risk-sharing, emphasises patient investment, entrepreneurship, data-enabled mudaraba and musharaka, employee ownership and partnerships that connect financial returns with real economic activity. The fourth shift, from elite access to democratised wealth, focuses on making investment opportunities accessible to ordinary savers through professionally governed and transparent platforms.
Finally, the shift from compliance to consciousness recognises that rules and technology alone cannot create lasting trust. Ethical character, accountability and genuine concern for others must guide institutional behaviour. Together, these shifts present a vision of Islamic finance that measures success not only through financial performance, but also through its contribution to human dignity and shared prosperity.
Chapter 3 | The Next Fifty Years of Islamic Finance - From Compliance to Consciousness, Capital as Amana, Economies of the Heart
70 | Global Islamic Finance Report 2026
Waqf:TheEndowmentThatBuiltaCivilisation
Waqf represents one of the most enduring examples of Islamic civilisation's approach to creating lasting social and economic value. For centuries, endowments supported hospitals, universities, libraries and essential public services without relying entirely on state funding (Çizakça, 2000). At its core, waqf is based on the preservation of principal while directing the benefits generated by an asset towards a designated charitable or social purpose. This structure makes it an early example of perpetual capital, in which the original asset remains protected while its income continues to serve future generations. History offers the example of the Well of Rumah, associated with Hazrat Usman ibn Affan (RA). The well was purchased for the benefit of the Muslim community, and its story illustrates how an endowed asset can continue generating value over an extended period.
Waqf 2.0 proposes professionally governed, transparent and productive endowments that can become a significant pillar of the modern Islamic economy
The transformation from a well into a palm grove and, eventually, income-generating property demonstrates the potential of carefully managed endowments. However, the historical development of waqf was disrupted by colonial systems, and many institutions
The Next Fifty Years of Islamic Finance - From Compliance to Consciousness, Capital as Amana, Economies of the Heart | Chapter 3
Global Islamic Finance Report 2026 | 71
have not yet fully restored its economic role. Waqf 2.0 proposes professionally governed, transparent and productive endowments that can become a significant pillar of the modern Islamic economy
Waqf 2.0 presents a modern approach to reviving the economic and social potential of waqf through professional management, investment and technology. The model begins with permanent capital, which may come from traditional awqaf, family philanthropy, zakat-related initiatives, corporate giving or impact-first investors. Rather than allowing these resources to remain disconnected from productive activity, the framework proposes investable delivery through professionally governed funds and special-purpose vehicles. These structures can support schools, clinics, housing, food security, clean energy projects and small and medium-sized enterprises. FinTech distribution is another important element, as digital identity, low-cost participation, transparent reporting and secure access can make waqf-related investment and giving more accessible. A focus on verified outcomes ensures that institutions measure the people served, jobs sustained, educational improvements achieved and emissions reduced.
Blended finance is a further element, in which philanthropic capital absorbs justified early risks, commercial investors participate in risk-adjusted opportunities, and governments or development finance institutions provide guarantees or outcome-based payments where appropriate. This arrangement can mobilise larger pools of private capital while preserving the original social purpose of waqf. The central message is that waqf should not replace markets or
Chapter 3 | The Next Fifty Years of Islamic Finance - From Compliance to Consciousness, Capital as Amana, Economies of the Heart
71 | Global Islamic Finance Report 2026
operate only as charity; instead, it can help design better markets that combine financial sustainability with measurable social benefit.
Takaful:TheGoldMineofIslamicFinance
There is a paradox at the heart of our industry. Takaful embodies the purest expression of Islamic finance: mutual assistance (ta'awun) and voluntary contribution (tabarru'), a community pooling its resources so that the misfortune of one is carried by the many. Yet it remains the smallest segment of the industry. Global takaful contributions are estimated at only around US$35 billion a year, well under one per cent of the industry's total assets. while insurance penetration across most Muslim-majority economies remains a fraction of the global average. I do not read this gap as a weakness. I read it as the industry's greatest unrealised opportunity. Takaful is the gold mine of Islamic finance.
I have long described takaful as the transformer of Islamic finance. An electrical transformer converts power from one voltage to another so that it can travel safely and arrive usefully. Takaful performs the same function for risk and for wealth. In one direction, it steps risk down: catastrophic risks that no single household can bear, the loss of a breadwinner, serious illness, fire, flood or crop failure, are converted into small, affordable, shared contributions. In the other direction, it steps savings up: the modest, regular contributions of millions of participants are aggregated into large pools of patient, long-term capital that can be invested in productive assets, housing, infrastructure and enterprise. Protection for the participant and investment for the real economy are achieved within a single structure. This is the transformer concept, and it is why
The Next Fifty Years of Islamic Finance - From Compliance to Consciousness, Capital as Amana, Economies of the Heart | Chapter 3
Global Islamic Finance Report 2026 | 71–72
takaful sits at the centre of any serious vision for the next fifty years.
Global takaful contributions are estimated at only around US$35 billion a year, well under one per cent of the industry's total assets – the industry’s greatest unrealised opportunity
Takaful is also a powerful instrument for the democratisation of wealth, the fourth of the five shifts described above. Its mutual architecture makes every participant a member rather than merely a customer: the underwriting surplus belongs to the pool, and the pool's investments belong, in economic substance, to the participants. Family takaful combines protection with disciplined long-term saving, giving ordinary households a professionally managed pathway into investment that was historically reserved for the affluent. Digital distribution and micro-takaful now allow this pathway to reach gig workers, smallholders, micro-entrepreneurs and low-income families at a cost per participant that was unimaginable a generation ago. A takaful industry at scale would therefore do for Islamic finance what pension and insurance capital did for the industrialised economies: create the deepest pools of long-term institutional capital, owned in substance by ordinary people.
The same mutuality principle can extend the industry's risk-management frontier. Kafala and takaful-based structures can provide
Chapter 3 | The Next Fifty Years of Islamic Finance - From Compliance to Consciousness, Capital as Amana, Economies of the Heart
72 | Global Islamic Finance Report 2026
credit enhancement and guarantees for SME finance. Cooperative pools can allow businesses to manage real exposures, from currency risk to the mismatch between fixed and floating obligations, through mutual risk-sharing arrangements rather than speculative derivatives. Mining this gold mine will require deliberate investment: retakaful capacity, actuarial and investment talent, digital-first operating models, sound consumer protection and supportive regulation. But if takaful penetration across our markets merely converged towards global norms over the coming decades, the result would transform household resilience, deepen capital markets and give Islamic finance its most authentic engine of inclusive growth. Like every gold mine, its value is real, but it must be mined with skill, patience and conviction.
The recurring instability of modern finance is not an accident; it is built into the architecture of fractional-reserve banking. Institutions fund long-term, risky and illiquid assets with short-term deposits that are promised back at par on demand. When confidence falters, the model fails, and the state steps in with deposit insurance, liquidity support and bailouts. Gains are privatised in good times and losses are socialised in bad times, precisely the inversion of responsibility that the amana principle rejects.
There is a distinguished body of thought, from the heart of Western economics, that reaches the same conclusion. Irving Fisher and the Chicago economists of the 1930s proposed full-reserve, or narrow banking in which payment deposits are backed one hundred per cent by safe assets and credit is financed by investors who
The Next Fifty Years of Islamic Finance - From Compliance to Consciousness, Capital as Amana, Economies of the Heart | Chapter 3
Global Islamic Finance Report 2026 | 72
knowingly bear risk. Researchers at the International Monetary Fund revisited the Chicago Plan with modern modelling tools and found its claimed benefits, dramatically reduced bank runs and business-cycle volatility to be supported. Laurence Kotlikoff has argued for limited purpose banking, in which banks operate as pass-through mutual funds that intermediate risk rather than warehouse it.
Full-reserve or narrow banking in which payment deposits are backed one hundred per cent by safe assets and credit is financed by investors who knowingly bear risk
What is striking is that this is precisely the classical model of Islamic banking theory. The two-tier mudaraba framework envisaged safekeeping deposits held in trust and fully available for payments, alongside investment accounts in which returns and risks pass through to the account holder as an investor. Writing at the International Monetary Fund, Mohsin Khan demonstrated that an Islamic system built on equity-like investment accounts adjusts to shocks more stably than a conventional system built on fixed-value liabilities, because asset losses are absorbed smoothly rather than triggering runs. In other words, the most rigorous conventional thinking on financial stability has been converging, for ninety years, on the model our own tradition proposed at the outset.
Chapter 3 | The Next Fifty Years of Islamic Finance - From Compliance to Consciousness, Capital as Amana, Economies of the Heart
72–73 | Global Islamic Finance Report 2026
The proposition for the next fifty years is therefore structural, not cosmetic. Islamic financial institutions should progressively re-architect intermediation around asset management contracts. Payments and safekeeping should be provided through fully backed deposits. Financing should be delivered through professionally governed mudaraba and wakala structures, funds and platforms in which the institution acts as a fiduciary manager, transparent about performance, remunerated for stewardship, and standing alongside, not above, the investors it serves. This is Bogle's fiduciary ideal expressed in the grammar of our own contracts. It would give practical effect to the shift from debt bias to risk-sharing at the level of system design rather than product labelling, and it would position Islamic finance not as a variant of a fragile model, but as a leader of a safer one. Regulators have a vital enabling role: recognising investment-account intermediation, requiring transparent pass-through of returns, and ensuring a level tax and prudential playing field for risk-sharing structures.
Islamic private equity in practice highlights the importance of avoiding destructive sectors, restraining excessive leverage, partnering with management and investing in productive businesses rather than relying solely on rent-generating assets
The Next Fifty Years of Islamic Finance - From Compliance to Consciousness, Capital as Amana, Economies of the Heart | Chapter 3
Global Islamic Finance Report 2026 | 73
FromPaperAssetstoProductiveAssets
The transition from paper assets to productive assets reflects a broader vision for Islamic asset management that connects investment with the real economy. Instead of focusing primarily on financial instruments, institutions are encouraged to direct capital towards sectors that address essential human and economic needs. Healthcare investment can support hospitals, clinics, medical services and health-related innovation, while education funding can strengthen schools, universities, training programmes and knowledge development. Infrastructure remains another important priority because transport, utilities, digital connectivity and public facilities provide the foundations for sustainable economic growth. Agriculture can benefit from investment in modern farming, food security, irrigation and supply chains, particularly in communities where livelihoods depend on land and natural resources.
Technology offers opportunities for innovation, productivity, digital access and new business models. Housing and SMEs are equally significant because affordable housing contributes to social stability, while small and medium-sized enterprises create employment, entrepreneurship and local economic activity. In a similar spirit, Islamic private equity in practice highlights the importance of avoiding destructive sectors, restraining excessive leverage, partnering with management and investing in productive businesses rather than relying solely on rent-generating assets. Ultimately, the authenticity of Islamic finance can be assessed through the quality of the economy it helps create, including stronger enterprises, greater employment and improved community capability.
Chapter 3 | The Next Fifty Years of Islamic Finance - From Compliance to Consciousness, Capital as Amana, Economies of the Heart
Artificial intelligence is the defining general-purpose technology of our era, and finance is among the industries it will reshape most profoundly. Used well, AI can advance every one of the five shifts. It can extend credit assessment to households and small businesses with no formal financial history, bringing the excluded into the system. It can collapse the cost of financial advice and portfolio management, democratising services once reserved for the wealthy. It can strengthen Shari'a governance through intelligent screening, monitoring and research support, and it can sharpen the measurement of social outcomes that a purpose-driven industry requires. But intelligence is not wisdom. An algorithm optimises whatever objective it is given; it does not ask whether the objective is just. Left ungoverned, AI can entrench bias in credit decisions, manipulate behaviour, erode privacy, and accelerate speculation to machine speed.
The question before us is therefore not what artificial intelligence can do, but what we ask of it, and who remains accountable for the answer. Here our tradition speaks with clarity. The human being is khalifa, a trustee, and accountability for every decision, including every automated decision, remains a human amana that cannot be delegated to a machine.
This is what I mean by pairing artificial intelligence with moral and spiritual intelligence. Moral intelligence supplies the guardrails: fairness, transparency, human oversight and accountability, principles now echoed in emerging global frameworks such as UNESCO's Recommendation on the Ethics of Artificial Intelligence and the Rome Call for AI Ethics, which leaders of the Abrahamic faiths,
The Next Fifty Years of Islamic Finance - From Compliance to Consciousness, Capital as Amana, Economies of the Heart | Chapter 3
Global Islamic Finance Report 2026 | 74
including senior Muslim institutions, have jointly embraced. Spiritual intelligence supplies the direction: aligning what we build with the maqasid al-Shari'a — the protection and promotion of faith, life, intellect, family and wealth. Islamic finance should not be a passive adopter of this technology. It should be a standard-setter, developing maqasid-aligned AI governance, insisting on human accountability in the loop, and deliberately deploying AI where it serves inclusion, zakat and waqf effectiveness, and the wellbeing of ordinary people. Technology guided by conscience can help create a better world for all; technology without conscience will simply make the old failures faster.
Blockchain:AuthenticityandIntegritybyDesign
Islamic finance is, at its heart, a promise about authenticity: that financing is connected to real assets and real economic activity, that risk is genuinely shared, and that contracts mean what they say. Distributed ledger technology is significant for our industry because it allows that promise to be engineered into the plumbing of finance itself. Immutable records establish a single version of the truth. Smart contracts execute agreed terms faithfully and automatically, narrowing the space for dispute and manipulation. Transparent ledgers allow ownership of underlying assets, and the flow of funds, to be traced from end to end.
The applications across our industry are practical and already visible. In the capital markets, Blockchain can reduce the cost and complexity of sukuk issuance and servicing while proving the existence and performance of underlying assets, a direct answer to the critique of form over substance. Al Hilal Bank executed the first sukuk transaction on Blockchain in 2018, and the world's first primary
Chapter 3 | The Next Fifty Years of Islamic Finance - From Compliance to Consciousness, Capital as Amana, Economies of the Heart
74 | Global Islamic Finance Report 2026
sukuk issuance on a public blockchain followed in 2019, a mudaraba micro-sukuk that funded Indonesian micro-entrepreneurs through a genuine profit-sharing structure. That small transaction carried a large message: technology can make authentic risk-sharing viable at micro scale and open the capital markets to issuers and investors who were never able to access them. Beyond the capital markets, distributed ledgers can bring verifiable integrity to zakat, sadaqa and waqf flows, so that every contributor can see that funds reached their intended purpose; to halal supply chains; to trade finance documentation; and to identity and know-your-customer processes that today exclude the undocumented.
A note of humility is warranted. Blockchain strengthens the integrity of processes; it cannot substitute for the integrity of character. A distributed ledger can prove what was done. Only conscience can decide what ought to be done. Used in that spirit, as an instrument of transparency, traceability and trust, this technology can bring greater authenticity to the business processes of Islamic finance and give practical, auditable expression to the industry's founding claims.
The Next Fifty Years of Islamic Finance - From Compliance to Consciousness, Capital as Amana, Economies of the Heart | Chapter 3
Global Islamic Finance Report 2026 | 74
Al Hilal Bank executed the first sukuk transaction on Blockchain in 2018, and the world's first primary sukuk issuance on a public blockchain followed in 2019, a mudaraba micro-sukuk that funded Indonesian micro-entrepreneurs through a genuine profit-sharing structure
The greatest bequest of the pioneers was not institutions; it was people. Every market, standard and framework described in this chapter was built by men and women who were themselves deliberately formed: taught, mentored, stretched and trusted. The next fifty years will be decided in exactly the same way. Human capital is the true infrastructure of Islamic finance, and it does not develop by accident. We must be honest about the gaps. There is still no widely available, foundation-level programme that equips the thousands of professionals who enter our industry each year from accounting, audit, consulting, law and conventional banking with a rigorous, practical grounding in Islamic finance.
Too much of what is taught remains theoretical, while practitioners need knowledge that is practically implementable on the desk, in
Chapter 3 | The Next Fifty Years of Islamic Finance - From Compliance to Consciousness, Capital as Amana, Economies of the Heart
75 | Global Islamic Finance Report 2026
the deal and in the boardroom. The industry has under-invested in the structured early-career formation, graduate programmes and internships, through which every great profession renews itself. Experience shows what works. At HSBC Amanah, we invested in a dedicated graduate and management development programme, and the professionals it formed now lead institutions across the global industry; the compounding return on that investment has exceeded any transaction we completed. Conferences and summits, when designed with intent, are not ceremonial gatherings but living platforms where scholarship meets practice and where the next generation meets its role models. Workshops that are case-based and implementable, executive education partnerships with serious universities, and industry publications such as this Report — these itself all form part of the same learning ecosystem.
The proposition is simple. Every Islamic financial institution should commit to a structured graduate trainee intake and internship programme, however modest, and treat learning and development as a first-order strategic investment rather than a discretionary cost. Industry platforms should collaborate to build a recognised foundation curriculum for new entrants and practical, product-level workshops for practitioners. The funding of education, research and scholarship should be placed on a permanent footing, ideally through endowed structures — a waqf for Islamic finance knowledge —so that the formation of people is as protected and perpetual as the endowments described earlier in this chapter. Platforms that promote learning and development, through conferences, workshops, graduate trainee schemes and internships, will always be the building block of the future of the Islamic finance industry.
The Next Fifty Years of Islamic Finance - From Compliance to Consciousness, Capital as Amana, Economies of the Heart | Chapter 3
The broader vision of responsible Islamic finance can be translated into three practical commitments for institutions. The first commitment is to adopt one measurable purpose mandate. Rather than attempting to address every social challenge simultaneously, an institution should identify a genuine problem, such as SME finance, housing, healthcare, education, food security, climate action or waqf development, and allocate capital towards a specific, measurable objective. This approach encourages focus, accountability and the ability to evaluate real results. The second commitment is to build one partnership beyond the institution's usual comfort zone. Meaningful progress often requires collaboration among banks, asset managers, regulators, FinTech companies, universities, waqf authorities and community organisations.
Each partner contributes different expertise, resources and perspectives, allowing financial capital to support ideas, education, infrastructure and human capability more effectively. The third commitment is to publish the consequences of financial decisions. Institutions should report where money was invested, what risks were shared, who benefited and what changed as a result. Transparent reporting helps stakeholders distinguish genuine impact from broad declarations of purpose. The potential cumulative effect is considerable: if more than 1,500 institutions adopt credible and repeatable solutions, collective action — supported by measurable objectives and transparent reporting — can turn individual institutional commitments into meaningful economic and social transformation.
Chapter 3 | The Next Fifty Years of Islamic Finance - From Compliance to Consciousness, Capital as Amana, Economies of the Heart
75–76 | Global Islamic Finance Report 2026
AnAllianceofGoodness
On a broader note, Islamic financial institutions need to build an Alliance of Goodness: a network of cooperation as a foundation for addressing the major challenges facing humanity. Climate change, poverty, food insecurity, healthcare and education are not problems belonging exclusively to one religion, region or civilisation. They affect communities across the world and therefore require shared responsibility and collective action. Islamic finance brings distinctive contributions to this alliance: the traditions of amana, or trust and responsibility, risk-sharing, restraint in the circulation of wealth and service to creation. Together, these principles encourage financial institutions to consider the wider consequences of their decisions and to ensure that capital serves purposes beyond individual gain. At the same time, Islamic finance can learn from other fields and traditions. Impact investing offers useful methods for measuring social and environmental outcomes, while global asset management demonstrates how capital can be mobilised at scale.
Islamic finance brings distinctive contributions to the alliance of goodness: the traditions of amana, or trust and responsibility, risk-sharing, restraint in the circulation of wealth and service to creation
The Next Fifty Years of Islamic Finance - From Compliance to Consciousness, Capital as Amana, Economies of the Heart | Chapter 3
Global Islamic Finance Report 2026 | 76
Technology can widen participation and improve access, and civil society provides valuable knowledge of local needs and community realities. Here the intellectual contributions of Adam Smith and John Bogle must also be noted, particularly in relation to moral responsibility and accessible investment. The central message is that differences in belief do not have to prevent cooperation. When people focus on what they can build together, shared values become a source of constructive partnership and lasting benefit.
EconomieswithaHeart
Economies with a Heart expresses the central vision of a financial system that combines economic productivity with ethical responsibility and human concern. Drawing on Adam Smith's observation that people possess principles that interest them in the fortune and happiness of others, it challenges the idea that financial success should be measured only through profit, growth or the number of products delivered. Instead, it proposes an economy in which capital understands its purpose and technology expands participation in meaningful ways.
Waqf is presented as an institution capable of regaining its wider civilisational role by supporting long-term social and economic development. Enterprise is recognised as a means of creating dignity through employment, entrepreneurship, innovation and productive opportunity. Profit remains an important and legitimate component of economic activity, but it should serve a broader purpose rather than becoming the sole measure of success. The emphasis is that prosperity based on strong institutions and individuals is connected with the amelioration of vulnerable communities. This perspective encourages financial organisations to consider how their
Chapter 3 | The Next Fifty Years of Islamic Finance - From Compliance to Consciousness, Capital as Amana, Economies of the Heart
76 | Global Islamic Finance Report 2026
decisions affect people with fewer resources and opportunities. Ultimately, the success of the Islamic finance industry should not be judged simply by the number of products it certifies. Its deeper contribution lies in the lives it improves, the opportunities it creates and the dignity it helps restore. This is the foundation of an economy guided by both efficiency and conscience.
There are three relationships which must be strengthened to achieve economies with a heart, and each demands a different kind of accountability. The first is with our forefathers: did we build upon the good they left behind, strengthen what they established, and honour the trust they placed in our hands? The second is with the Prophet (SAW): when we look at our institutions, balance sheets, transactions and boardrooms, do they reflect the akhlaq, the honesty, mercy, fairness and generosity he embodied? Have we translated those qualities from ideals into institutional practice? The third, and ultimately the most consequential, is with Allah SWT. He blessed us with resources, wealth, networks and knowledge. Did we do our very best to make the world a better place?” These are not merely questions of professional performance or institutional success. They go to the heart of what it means to hold wealth and capital as an amana. If capital is truly an amana, then these are the three audits that matter most. Unlike quarterly reviews, annual reports or regulatory assessments, however, they cannot be postponed. They are audits for which preparation must begin today.
The Next Fifty Years of Islamic Finance - From Compliance to Consciousness, Capital as Amana, Economies of the Heart | Chapter 3
This paper advances a single, cumulative argument: the strategic destination for Islamic sustainable finance is not a lightly greened linear enterprise but a regenerative business form in which circularity, impact materiality, stakeholder governance, and real-economy-linked Islamic contracts reinforce one another. The argument is organised around a Cartesian coordinate system of competing business forms, defined by two strategic tensions—the treatment of Nature on the horizontal axis and the treatment of Society on the vertical axis. The four quadrants of that system are read not as a static taxonomy but as distinct organisational logics and as transition vectors between them: linear open-loop extraction (Q3), disclosure-led linear-ESG (Q2), technically circular but socially blind closed-loop operations (Q4), and a higher-order Circular-Maqasid-ESG synthesis (Q1).
The paper defines Q1 as Regenerative Sustainability: the simultaneous and mutually non-substitutable regeneration of Nature, of Society, and of the Economy itself. Treating the contract form as behavioural architecture rather than as a neutral funding vessel, the paper then derives a suite of Islamic product designs suited to Q1
transition—servitised ijara structures, use-of-proceeds circular sukuk, blended musharaka and mudaraba climate-circular funds, waqf-backed and zakat-supported MSME transition facilities, and circular takaful mechanisms that underwrite durability, maintenance, and repair. These designs consolidate a prior research programme on venture waqf and equity-at-default, on blended Islamic finance for impactful enterprises, and on Islamic finance as an embedded framework for regenerative development and are tested through a worked application to geothermal (ground-source) heat pumping—a long-lived, capital-heavy asset whose deployment is constrained more by financing structure than by technology. Islamic finance is shown to be distinctively suited to this destination because of its emphasis on asset-backing, risk-sharing, and social solidarity, but the paper insists throughout that realising the potential depends on stronger taxonomies, disclosure systems, Shari’a governance, and impact reporting, which are constitutive elements of the model rather than optional accessories.
TheArgumentandItsStakes
The linear economic model remains the dominant organisational logic across most industries. Its basic pattern—extract, manufacture, sell, use, and discard—has been criticised by major policy and research institutions as environmentally and socially unsustainable because it locks firms into continued virgin-resource extraction, rising waste, and avoidable emissions. In response, the circular economy has matured into a systems framework orientated around eliminating waste and pollution, circulating products and materials at their highest value, and regenerating natural systems. The scholarly literature treats circular business models not as end-of-pipe
Circular-ESG Business Transformation and the Design of Islamic Financial Products | Chapter 5
Global Islamic Finance Report 2026 | 93–96
Chapter Highlights
Figure 4.1: Cartesian Four-Quadrant Coordinate System of Business Forms for Nature and Society
High Positive Social Impact
Value Extraction (Natural Systems Depletion)
Q2 (−,+)
Linear-open Loop
Values-shifted but Nature-negative
Mission-led yet resource intensive
Strong social intent
Limited or negative natural regeneration
Q1 (+,+)
Circular Maqasid-ESG
Regenerative & Purpose-centric
Holistic maqasid alignment
Restores & regenerates nature
Creates long-term social prosperity
Q3 (−,−)
Linear-open Loop
Extractive & Value-depleting
Profit over people & planet
High extraction & pollution
Weak or exploitative models
Q4 (+,−)
Circular Closed-loop
Nature-Positive but Society-negative
Environmentally efficient operations
Low social inclusion or inequitable distribution
Technically circular but socially blind
Y-SOCIETY
Natural Systems Regeneration
Value ExtractionDeplete Nature & Society
Low / Negative Social Impact
Value CreationRegenerate Nature & Elevate Society
LEGEND
ERA OF R (Restorative Era)RRefuseRRethinkRReduceRReuseRRepair / RefurbishRRemanufactureRRepurposeRRecycleRRecover
ERA OF D (Design Era)D1Design to facilitate the RsD2Design to durabilityD3Design to reduce emissions and pollutantsD4Design financial contracts to support the transitionD5Design supportive policiesD6Design supportive technologies
Nature Axis (X): From degrading to regenerating natural systemsSociety Axis (Y): From self-serving to uplifting human well-being
PURPOSE: Guide business forms from value extraction (Q3) → efficiency (Q4) → values integration (Q2) → regeneration (Q1).The future belongs to business models that regenerate Nature and elevate Society.
Note: The horizontal axis (X: Nature) runs from value extraction to natural-systems regeneration; the vertical axis (Y: Society) runs from low or negative social impact to high positive social impact. Q1 = Circular-Maqasid-ESG (regenerative and purpose-centric); Q2 = linear open-loop, values-shifted but nature-negative; Q3 = linear open-loop, extractive and value-depleting; Q4 = circular closed-loop, nature-positive but society-blind. The “Era of R” (Refuse, Rethink, Reduce, Reuse, Repair/Refurbish, Remanufacture, Repurpose, Recycle, Recover) and the “Era of D” (design strategies) summarise the operational and design levers of the regenerative quadrant.
Chapter Highlights
A Worked Application
Financing Geothermal Heat Pumping
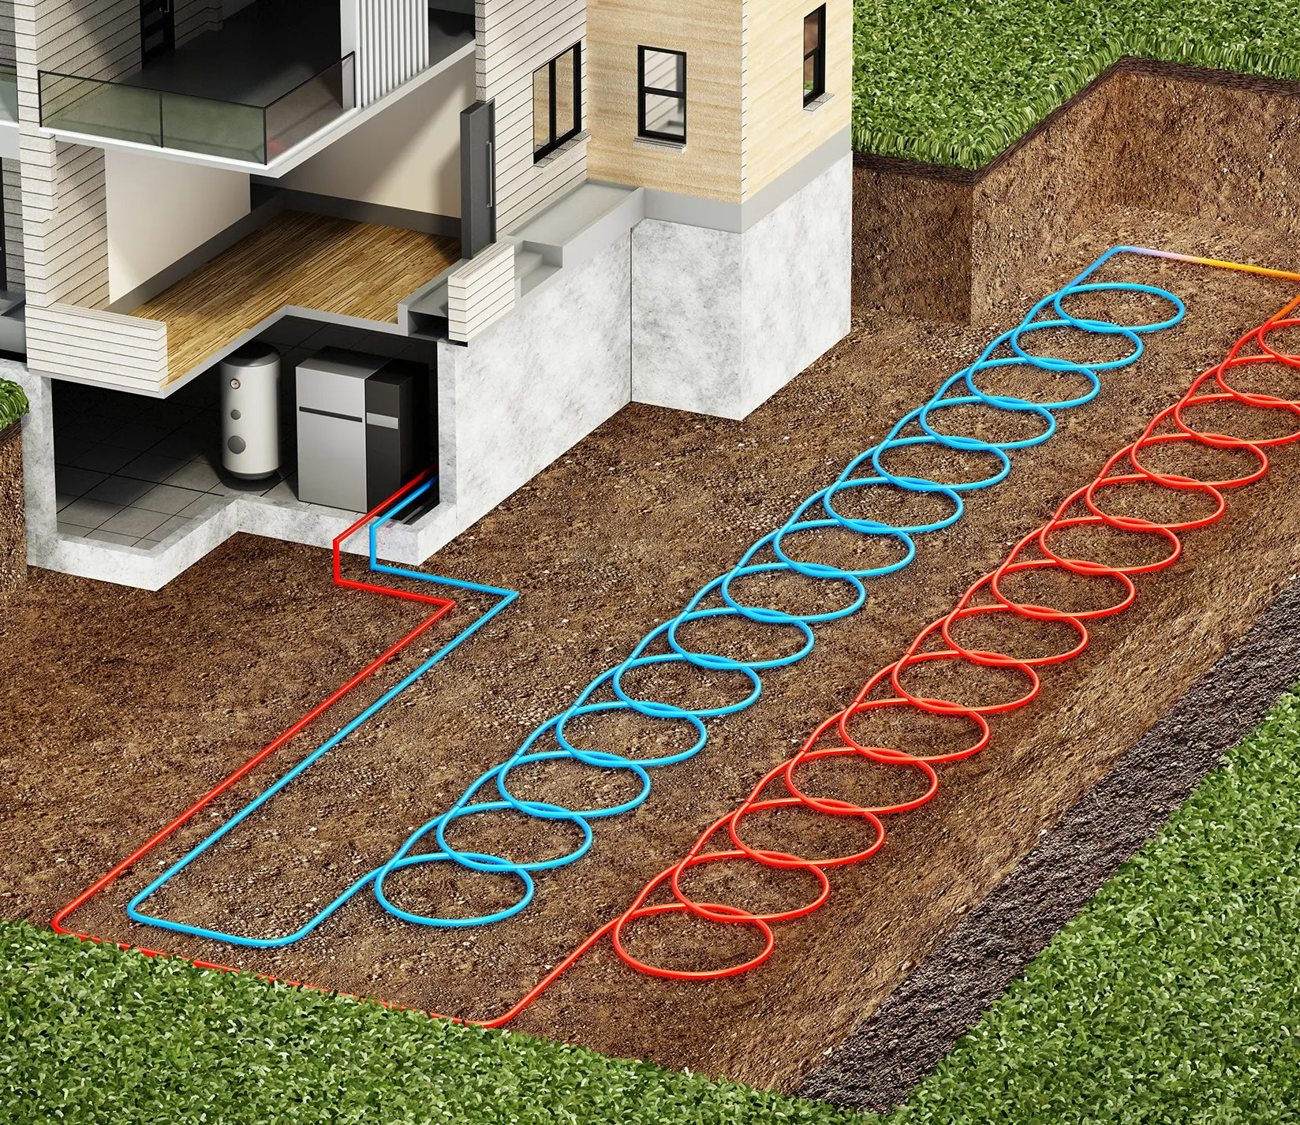
Geothermal—or, more precisely, ground-source—heat pumping offers a near-ideal test of the framework because its difficulty is financial before it is technical. A ground-source system moves heat between a building and the stable temperature of the earth a few metres down, delivering both heating and cooling at a coefficient of performance several times that of combustion or electrical resistance, and the buried ground loop can last fifty years or more. At district scale, the University of Toronto’s King’s College Circle geoexchange—Canada’s largest urban ground-source system, comprising 372 boreholes drilled 250 metres deep and completed in 2024—provides heating and cooling to more than thirty campus buildings while avoiding roughly 15,000 tonnes of carbon dioxide equivalent each year.
waste management but as mechanisms that narrow, slow, close, intensify, and dematerialise resource loops.
Running in parallel, sustainability governance has increasingly been organised through the vocabulary of ESG. That development has sharpened board-level attention to sustainability-related risks, metrics, and disclosure, especially since the issuance of IFRS S1 and IFRS S2, which require entities to disclose sustainability, climate-related risks and opportunities that could affect enterprise prospects, cash flows, access to finance, and cost of capital. Yet ESG remains an ambiguous field. Berg et al. (2022) documented substantial disagreement among the major rating providers and traced most of the divergence to measurement differences. The practical hazard is that a firm may improve one rating while neglecting broader sustainability performance and that investors may mistake disclosure sophistication for real-economy transformation.
A second and deeper limitation is that mainstream ESG architecture often privileges financially material information for capital providers. By contrast, the Global Reporting Initiative (2021a) centres an organisation’s significant impacts on the economy, environment, and people, and EFRAG’s (2024) implementation guidance formalises double materiality by requiring consideration of both impact materiality and financial materiality. This distinction is decisive for circular transformation: a firm can be ESG-literate in a disclosure sense while remaining materially linear in how it designs products, sources inputs, handles waste, and shares value with labour and communities. Circular transition, therefore, demands more than compliance-minded governance; it demands restructuring the business model itself.
Chapter 5 | Circular-ESG Business Transformation and the Design of Islamic Financial Products
96 | Global Islamic Finance Report 2026
Maqasid al-Shari’a has been treated as a framework capable of aligning the protection of life, wealth, intellect, lineage, and religion with contemporary sustainability concerns
Islamic finance enters this conversation by a different moral and institutional route. Policy and scholarly sources consistently emphasise that it is anchored in real economic activity, risk sharing, sanctity of contract, and social justice. The World Bank and Islamic Financial Services Board note that Islamic finance strengthens the link between finance and the real economy through asset-backing and risk sharing, while the IFSB (2020) explains that the tradition weighs both individual and societal interests and that solidarity instruments—waqf, sadaqa, and qard—can be mobilised for inclusion and poverty alleviation. In recent scholarship on sustainable takaful and Islamic corporate sustainability, maqasid al-Shari’a has been treated as a framework capable of aligning the protection of life, wealth, intellect, lineage, and religion with contemporary sustainability concerns. These strands now matter in market practice. The global Islamic financial services industry reached US$3.38 trillion in assets in 2023. At the same time, the World Bank and Islamic Development Bank report that Islamic climate finance remains constrained by fragmented governance frameworks, the absence of a common taxonomy, limited human capability, thin project pipelines, and weak data infrastructure, even as Islamic banks, sustainable sukuk, and halal value chains increasingly engage with
Circular-ESG Business Transformation and the Design of Islamic Financial Products | Chapter 5
Global Islamic Finance Report 2026 | 96
sustainability strategies. The market, in short, is now large enough to matter but not yet institutionally mature enough to finance transition at scale.
The inquiry also builds on a sustained research programme that has, over the past decade, argued for exactly this kind of paradigm shift from within Islamic economics. Earlier work reconceived the waqf as an incorporated venture institution whose purpose is to make impactful, zero-waste halal enterprises successful and introduced equity-at-default as a compassionate contract that replaces collateral and foreclosure with partnership. Subsequent work engineered blended Islamic structures that mobilise social and commercial capital jointly for impactful small and medium enterprises pursuing the Sustainable Development Goals, and more recent work has framed Islamic economics and finance itself as an embedded framework for regenerative development aligned with maqasid al-Shari’a. The present paper consolidates these threads into a single coordinate logic and extends them from individual instruments toward a general account of regenerative business transformation. This paper develops its case thematically rather than through the conventional empirical sequence because the question at hand cannot be answered from any one piece of literature in isolation; it requires an integrative synthesis of circular-economy theory, sustainability-disclosure standards, Islamic governance standards, and market-structuring guidance. The argument proceeds in five movements. It first reconstructs the coordinate system as the analytical spine of the inquiry. It then reads the four quadrants as archetypes of the firm, devoting sustained attention to the linear, linear-ESG, circular, and circular-ESG forms.
It next establishes the design imperative—the claim that contract
Chapter 5 | Circular-ESG Business Transformation and the Design of Islamic Financial Products
96–97 | Global Islamic Finance Report 2026
form is itself behavioural architecture—and from that imperative derives a family of Islamic financial products fitted to the regenerative quadrant. It closes by specifying the measurement, governance, and policy conditions without which the model cannot be credible. The contribution is to connect circular business-model theory, disclosure materiality, and Islamic contract design into one integrated logic rather than three separate conversations.
ACoordinateSystemofCompetingBusinessForms
The organising device of this paper is a Cartesian coordinate system that captures, in a single visual grammar, four competing business forms across two directional tensions (Figure 1). The horizontal axis measures the treatment of Nature, running from value extraction and the depletion of natural systems on the left toward their restoration and regeneration on the right. The vertical axis measures the treatment of Society, running from self-serving conduct and low or negative social impact at the bottom toward the uplifting of human well-being at the top. Read this way, the rightward and upward movements are not static labels but strategic transition vectors: the right captures movement from extractive or weakly restorative activity toward circular and regenerative relations with ecological systems, and the upper region captures movement from narrow profit maximisation toward stronger social value, governance, and stakeholder obligation.
Two features of the figure deserve emphasis before the quadrants are examined individually. The first is that the axes are non-substitutable. A gain on the Nature axis does not license a loss on the Society axis, and vice versa; the plane refuses the compensatory logic by which strong performance in one domain is allowed to
Circular-ESG Business Transformation and the Design of Islamic Financial Products | Chapter 5
Global Islamic Finance Report 2026 | 97
offset weakness in another. The diagram’s value lies precisely in keeping the two tensions visible at once so that a firm cannot purchase ecological credit with social neglect or social credit with ecological harm. This refusal has deep roots in the Islamic principle of mizan—the balance set within creation that human conduct is enjoined not to transgress—which has long been read as an injunction against ecological and social imbalance alike. Non-substitutability is, in this sense, not merely an analytical convenience but a normative commitment. The second feature is more easily overlooked.
The token placed at the extractive origin of the lower-left quadrant—short-term profit, the economy reduced to throughput—reveals that the Economy is itself a third object that can be either depleted or regenerated. Although the plane is drawn with two axes, it therefore encodes a threefold claim about regeneration: of Nature, of Society, and of the Economy as a self-renewing rather than self-consuming system. That third regeneration becomes explicit only in the upper-right quadrant, and it is the conceptual heart of this paper.
FourArchetypesoftheFirm
The coordinate system becomes analytically powerful when each quadrant is read as a coherent archetype—a distinct way of organising value proposition, value creation, value delivery, and value capture—rather than as a mere quadrant label. There are at least four qualitatively different ways for a firm to respond to sustainability pressure, and the differences among them are differences of architecture, not of degree.
Chapter 5 | Circular-ESG Business Transformation and the Design of Islamic Financial Products
97 | Global Islamic Finance Report 2026
The Linear, Open-loop Firm (Q3)
The lower-left quadrant represents the linear, open-loop firm in its purest form: business-as-usual extraction, profit-centred and value-depleting. Here economic value remains detached from ecological regeneration and only weakly connected to social welfare. The firm’s posture corresponds closely to the European Commission’s (2023) critique of the take-make-use-dispose model and to the OECD’s (2019) characterisation of the traditional linear system of extraction, ownership, and of-life responsibility is externalised onto customers, communities, and ecosystems. The defining traits of this archetype are the prioritisation of short-term profit over people and planet, high extraction and pollution intensity, and weak or frankly exploitative treatment of labour and community. In coordinate terms, it sits at the negative pole of both axes—depleting Nature while doing little for Society—and it is the historical default from which every other archetype represents an attempted departure. Crucially, the linear firm is not irrational; within a price system that does not charge for waste, durability, or social harm, linearity is locally optimal. That observation matters because it implies that moving a firm out of Q3 will require changing the incentives it faces, not merely exhorting it to behave better.
Circular-ESG Business Transformation and the Design of Islamic Financial Products | Chapter 5
Global Islamic Finance Report 2026 | 97–98
Figure 4.1: Cartesian Four-Quadrant Coordinate System of Business Forms for Nature and Society
High Positive Social Impact
Value Extraction (Natural Systems Depletion)
Q2 (−,+)
Linear-open Loop
Values-shifted but Nature-negative
Mission-led yet resource intensive
Strong social intent
Limited or negative natural regeneration
Q1 (+,+)
Circular Maqasid-ESG
Regenerative & Purpose-centric
Holistic maqasid alignment
Restores & regenerates nature
Creates long-term social prosperity
Q3 (−,−)
Linear-open Loop
Extractive & Value-depleting
Profit over people & planet
High extraction & pollution
Weak or exploitative models
Q4 (+,−)
Circular Closed-loop
Nature-positive but Society-negative
Environmentally efficient operations
Low social inclusion or inequitable distribution
Technically circular but socially blind
Y-SOCIETY
Natural Systems Regeneration
Value ExtractionDeplete Nature & Society
Low / Negative Social Impact
Value CreationRegenerate Nature & Elevate Society
LEGEND
ERA OF R (Restorative Era)RRefuseRRethinkRReduceRReuseRRepair / RefurbishRRemanufactureRRepurposeRRecycleRRecover
ERA OF D (Design Era)D1Design to facilitate the RsD2Design to durabilityD3Design to reduce emissions and pollutantsD4Design financial contracts to support the transitionD5Design supportive policiesD6Design supportive technologies
Nature Axis (X): From degrading to regenerating natural systemsSociety Axis (Y): From self-serving to uplifting human well-being
PURPOSE: Guide business forms from value extraction (Q3) → efficiency (Q4) → values integration (Q2) → regeneration (Q1).The future belongs to business models that regenerate Nature and elevate Society.
Note: The horizontal axis (X: Nature) runs from value extraction to natural-systems regeneration; the vertical axis (Y: Society) runs from low or negative social impact to high positive social impact. Q1 = Circular-Maqasid-ESG (regenerative and purpose-centric); Q2 = linear open-loop, values-shifted but nature-negative; Q3 = linear open-loop, extractive and value-depleting; Q4 = circular closed-loop, nature-positive but society-blind. The “Era of R” (Refuse, Rethink, Reduce, Reuse, Repair/Refurbish, Remanufacture, Repurpose, Recycle, Recover) and the “Era of D” (design strategies) summarise the operational and design levers of the regenerative quadrant.
The Linear-ESG Firm (Q2)
The upper-left quadrant is the most seductive and the most easily
Chapter 5 | Circular-ESG Business Transformation and the Design of Islamic Financial Products
98–99 | Global Islamic Finance Report 2026
misread. It is the linear-ESG firm: values-shifted but still nature-negative, mission-led yet resource-intensive. This is an important intermediate form because it demonstrates that a firm can improve its governance, ratings, disclosure, and stakeholder language without fundamentally redesigning its products, supply chains, or ownership logic. Such firms adopt sustainability reports, climate disclosures, and board-level oversight; they cultivate social purpose, ethical engagement, and governance excellence; and they may, thereby, satisfy genuine investor and regulatory demands. IFRS S1 and S2 materially strengthen the discipline of governance, strategy, risk management, and target-setting that these firms can credibly demonstrate (IFRS Foundation, 2023a, 2023b).
A firm can improve its governance, ratings, disclosure, and stakeholder language without fundamentally redesigning its products, supply chains, or ownership logic by adopting sustainability reports, climate disclosures and board-level oversight
Yet the quadrant remains open-loop because none of this necessarily alters the material metabolism of the business. A company can produce sophisticated, financially material ESG disclosures while continuing to rely on planned obsolescence, low reparability, minimal take-back, and virgin-material intensity. The evidence on
Circular-ESG Business Transformation and the Design of Islamic Financial Products | Chapter 5
Global Islamic Finance Report 2026 | 99
rating divergence deepens the concern: because ESG measurement is itself noisy and contested, a firm can improve its position on one rater’s scale while leaving its real-economy footprint substantially untouched. The danger of Q2, then, is not that it is dishonest but that it is a plateau—a place where “more ESG” can be added indefinitely without the loop ever closing.
Recognising Q2 as a distinct archetype guards against the most common error in sustainable-finance practice: treating improved disclosure as if it were structural transformation. This caution applies with particular force to Islamic finance, and it is the one that the tradition’s own critics have pressed. Because the linear paradigm has been so dominant, Islamic finance and the broader halal economy have largely operated as a permissible subset of the extractive model rather than as an alternative to it, reproducing its throughput logic in Shari’a-compliant forM. Halal status, on this view, is necessary but not sufficient to make a business socially responsible or regenerative (Khan & Badjie, 2022). A firm may therefore be simultaneously Shari’a-compliant, ESG-disclosing, and squarely lodged in Q2—values-shifted in its language while linear in its metabolism. This is the sharpest warning the coordinate system issues to Islamic sustainable finance: compliance and disclosure together can still leave the loop open.
The Circular, Closed-Loop Firm (Q4)
The lower-right quadrant is operationally transformative in a way the left-hand quadrants are not. The circular, closed-loop firm redesigns products and asset flows around circular logic: it is nature-positive, but, as the figure warns, it can be technically circular yet socially blind. The circular-economy literature describes the
Chapter 5 | Circular-ESG Business Transformation and the Design of Islamic Financial Products
99 | Global Islamic Finance Report 2026
relevant mechanisms in complementary terms. Bocken et al. (2016) distinguishes slowing, closing, and narrowing resource loops; Geissdoerfer et al. (2020) extends this with intensifying and dematerialising loops; and the OECD (2019) identifies circular supply, resource recovery, product life extension, sharing models, and product-service systems as the headline circular business models. The Q4 firm puts these into practice: it redesigns supply chains, extends product life through eco-efficient design, recovers value at end of use, and depollutes and restores natural systems where it can.
What this archetype does not guarantee is a comprehensive social logic. The figure is careful to label Q4 as nature-positive but society-negative, with low social inclusion or inequitable distribution as its characteristic shortfall, and the empirical literature supplies the corresponding caution: the OECD (2019) explicitly warns that circular models, though broadly favourable on life-cycle environmental grounds, can generate rebound effects and unintended consequences if they are not assessed systemically. A firm can close its material loops and still concentrate the resulting gains, displace labour, or deepen inequality. Circularity is thus a necessary advance over linearity, but it is not, by itself, regeneration. It solves the Nature axis while leaving the Society axis unaddressed.
The Circular-Maqasid-ESG Firm (Q1): Regenerative Sustainability
The upper-right quadrant is the conceptual destination of this paper, and it is emphatically not a synonym for recycling or for sustainability reporting. It is a higher-order synthesis, and it is best defined directly.
Circular-ESG Business Transformation and the Design of Islamic Financial Products | Chapter 5
Global Islamic Finance Report 2026 | 99–100
Circularity is thus a necessary advance over linearity, but it is not, by itself, regeneration. It solves the Nature axis while leaving the Society axis unaddressed
Q1 Regenerative Sustainability is defined here as the condition in which a business form achieves the simultaneous and mutually non-substitutable regeneration of three domains at once—Nature, Society, and the Economy—so that progress in any one is achieved without sacrificing the others and ideally reinforces them.
Each of the three regenerations has a distinct content. The regeneration of Nature is carried out operationally by what the figure calls the Era of R—refuse, rethink, reduce, reuse, repair, refurbish, remanufacture, repurpose, recycle, and recover—whose cumulative effect is to restore rather than deplete natural systems . The regeneration of Society is carried by maqasid al-Shari’a, which orients the firm toward the protection of life, intellect, lineage, wealth, religion and toward long-term social prosperity and inclusion rather than narrow shareholder return; read together with the Sustainable Development Goals and the pillars of sustainable human development, with which the maqasid substantially converge. The regeneration of the Economy is the most distinctive and the most easily missed: it requires that the financial and contractual layer be redesigned so that value capture rewards durability, maintenance, and recovery rather than throughput so that the economy becomes
Chapter 5 | Circular-ESG Business Transformation and the Design of Islamic Financial Products
100 | Global Islamic Finance Report 2026
a self-renewing system rather than a self-consuming one.
It is in this third regeneration that Islamic contract design does its decisive work, and it is the reason the regenerative quadrant cannot be reached by environmental engineering alone. This is the sense in which Islamic economics and finance can serve as an embedded framework for regenerative development rather than as an external overlay on a linear economy: the contractual layer is where regeneration is either secured or lost. Earlier work renders the financial markers of that regeneration concrete, extending the circular economy’s zero-waste and zero-emissions targets with two distinctively financial zeros—zero-interest and zero-foreclosures—so that the economy ceases to extract rent and ceases to liquidate enterprises in distress.
Circular-ESG Business Transformation and the Design of Islamic Financial Products | Chapter 5
Global Islamic Finance Report 2026 | 100
Seen in these terms, the three contributing disciplines occupy complementary places within Q1. Circularity governs the flow of resources and products. ESG contributes structured disclosure, board process, risk management, and capital-market visibility. Maqasid al-Shari’a supplies a thicker moral compass and a tighter fit between finance and the real economy. The empirical literature supports the coherence of this synthesis: the sustainable-takaful scholarship finds substantial convergence between ESG principles and maqasid, while cross-country evidence on Islamic banks indicates that stronger Shari’a governance improves social and governance performance even where environmental performance still lags. The upper-right quadrant should therefore be understood as the form in which circular design and Shari’a-informed governance jointly cure the “thinness” of both disclosure-led ESG and technically narrow circularity—the form in which the firm is at once materially circular and normatively accountable to Nature, Society, and the Economy.
The figure’s “Era of D” makes a final, practical point about how Q1 is reached. Regeneration depends repeatedly on design—design for the Rs, for durability, for reduced emissions, for financial contracts that support the transition, and for the supportive policies and technologies that surround it. European circular-economy policy now places durability, reparability, the right to repair, digital product information, and sustainable product design at the centre of transition strategy, and the business-model literature has long insisted that product design and business-model design must move together if firms are to slow and close their loops. The implication for finance is direct and is taken up next: products meant to support circular transformation must themselves be designed around asset longevity, maintainability, recoverability, and traceability, or
Chapter 5 | Circular-ESG Business Transformation and the Design of Islamic Financial Products
100 | Global Islamic Finance Report 2026
financing will remain misaligned with the very transition it claims to serve.
The transition from the left-hand quadrants to Q1 turns on a claim that is easy to state and consequential to accept: contract form is behavioural architecture. Islamic financial products are not neutral funding vessels whose only function is to move capital; they are governance technologies that shape conduct. A debt-like instrument that rewards volume tends to entrench throughput and short-term disposal, pulling even a well-intentioned firm back toward Q3. An ownership, leasing, or impact-linked structure, by contrast, can create standing incentives for maintenance, longer asset life, take-back, and better stakeholder treatment. This is why the same firm can behave linearly or regeneratively depending on how it is financed and why financing design is not downstream of business transformation but part of it.
Islamic finance offers a striking illustration of the same dynamic in reverse. A whole family of contracts that were originally compassionate—qard, kafala, daman, takaful, hawalat al-dayn, and tawarruq among them—has gradually been commercialised under the pressure of the linear paradigm, their solidarity function left dormant inside instruments now optimised for volume. Reaching Q1 partly means reactivating that dormant function: designing contracts that once again behave as institutions of compassion rather than as throughput machinery. This assumption is consistent with two bodies of literatures at once. Circular business-model scholarship insists that value capture must be aligned with the intended
Circular-ESG Business Transformation and the Design of Islamic Financial Products | Chapter 5
Global Islamic Finance Report 2026 | 100–101
pattern of value creation and delivery, or the model will not hold. Islamic finance scholarship stresses Shari’a governance, real-economy linkage, and social solidarity as the structuring principles of intermediation. Where the two literatures meet, the conclusion is the same: if a financier wishes to reward durability and recovery, it must use instruments whose returns are tied to durability and recovery rather than to sales volume.
Islamic financial products are not neutral funding vessels whose only function is to move capital; they are governance technologies that shape conduct
Reaching Q1 also requires a different view of materiality than the one that governs the linear-ESG quadrant. IFRS S1 and S2 focus on the sustainability- and climate-related risks and opportunities that are reasonably expected to affect enterprise prospects; the Global Reporting Initiative (2021a, 2021b) instead centres the firm’s significant impacts on the economy, environment, and people; and EFRAG’s (2024) double-materiality framework explicitly combines impact materiality and financial materiality and ties both to the value chain.
For a regenerative business form, the double view is decisive. A repair network, a reverse-logistics system, or a waqf-funded water project may matter because it protects communities or ecosystems
Chapter 5 | Circular-ESG Business Transformation and the Design of Islamic Financial Products
101 | Global Islamic Finance Report 2026
well before its effect crystallises as a short-term enterprise financial metric. In Islamic finance, this wider lens is not an imported novelty; it is consonant with maqasid and with the IFSB’s (2020) emphasis on social solidarity and inclusion. Materiality, properly understood, is therefore the bridge between the disclosure machinery of ESG and the regenerative ambition of Q1.
From the design imperative, five Islamic financial product families emerge as especially well-suited to financing the move into Q1. Each is presented not as an instrument already dominant in the market but as a design archetype derived from the capabilities and barriers documented in the reviewed literature. Each also draws on the reservoir of Islamic solidarity instruments—the institutions of compassion—whose regenerative potential can be deliberately re-engineered into modern product form.
The Servitised Ijara Transition Facility
Product-service-system research shows that circular firms frequently create value by providing access and performance rather than by transferring full ownership, and a Shari’a-compliant leasing architecture is unusually well matched to this logic. Under ijara, a financier or special-purpose vehicle can retain ownership of durable assets while the user pays for use, performance, or output. When that structure is combined with maintenance covenants, upgrade clauses, take-back requirements, and residual value planning, ijara can finance fleets, manufacturing equipment, water and cooling systems, or agricultural technologies in ways that reward
Circular-ESG Business Transformation and the Design of Islamic Financial Products | Chapter 5
Global Islamic Finance Report 2026 | 101–102
long asset life rather than rapid turnover. The mechanism is powerful precisely because ownership retention gives the financier a direct stake in designing for repair, refurbishment, and eventual recovery; the instrument fits both product-life-extension and product-service-system models, and it converts the financier from a seller of throughput into a steward of asset longevity.
The Use-of-Proceeds Circular Sukuk
Joint guidance from ICMA, the Islamic Development Bank, and the London Stock Exchange Group makes clear that sustainable-sukuk practice largely follows the architecture of sustainable bonds: a public framework aligned to use of proceeds, project evaluation and selection, management of proceeds, and reporting, supported by second-party opinions and post-issuance tracking. The market already recognises circular-economy categories as eligible use-of-proceeds areas, alongside eco-efficient products and production technologies, pollution prevention, renewable energy, water, and biodiversity. A circular sukuk could therefore fund repair hubs, remanufacturing ecosystems, industrial-symbiosis parks, reverse-logistics systems, secondary-material platforms, sustainable buildings, clean transport, or waste-to-value infrastructure. The WB-IsDB (2025) report documents growing issuance and continued oversubscription in the green-sukuk market while noting the need for more diversified pipelines and more innovative structures—precisely the room into which a circular sukuk is designed to move.
Chapter 5 | Circular-ESG Business Transformation and the Design of Islamic Financial Products
102 | Global Islamic Finance Report 2026
Product-service-system research shows that circular firms frequently create value by providing access and performance rather than by transferring full ownership, and a Shari’a-compliant leasing architecture is unusually well matched to this logic
The Blended Musharaka or Mudaraba Climate-circular Innovation Fund
Many circular business models need patient risk capital at the experimentation stage—repair platforms, circular materials science, refill systems, modular hardware, industrial-symbiosis software, and climate-resilient halal value chains seldom fit collateral-heavy lending. Here the risk-sharing instruments of Islamic finance comes into their own. The WB-IsDB (2025) report argues that Islamic finance has a strong opportunity to deploy mudaraba and musharaka for private-equity and venture-capital roles in climate innovation, and it presents a blended musharaka-sukuk model in which concessional and commercial capital are combined. A blended fund of this kind can absorb early-stage uncertainty while maintaining real-sector linkage and shared upside, which is exactly the financing profile that the formation of the upper-right quadrant requires and that conventional debt struggles to provide.
The structuring logic for such a fund has already been worked out
Circular-ESG Business Transformation and the Design of Islamic Financial Products | Chapter 5
Global Islamic Finance Report 2026 | 102
in detail. Blended Islamic finance brings three motivations into deliberate alignment—philanthropic compassion, commercial profit, and public-sector facilitation—around a consensus set of impact criteria for the enterprises it backs: the 4 Zeros and Service to Society, namely, zero-waste, zero-emissions, zero-interest, zero-foreclosures, and demonstrable benefit to the community. In the resulting structures, such as a blended murabaha or a blended murabaha line of credit, the commercial financier supplies the principal, a philanthropic or social-fund tranche underwrites the cost of funds, and the public sector facilitates so that the impactful enterprise receives subsidised or effectively interest-free financing while each party’s motive is satisfied. Islamic social funds—zakat, waqf, and sadaqa—can be layered as first-loss, subordinate, or guarantee (kafala) capital that de-risks commercial money, which is precisely the blended-finance architecture, in Shari’a-compliant form, that the WB-IsDB (2025) report now calls for.
The Waqf-Supported, Zakat-Enabled MSME Transition Facility
The regenerative quadrant cannot be reached by large firms alone; micro, small, and medium enterprises must transition too, and they are typically the businesses most likely to fall between commercial-bank requirements and public-funding gaps. The IFSB (2020) notes that waqf, sadaqa, and qard can be integrated with Islamic financial products to serve inclusion objectives, and the WB-IsDB (2025) report shows that in Indonesia and Malaysia, zakat and waqf already help halal-industry SMEs obtain certification and adopt sustainable practices, even as a lack of financial resources and low ESG technical capability remain major barriers. A Circular-Maqasid-ESG facility for MSMEs could therefore use a layered structure in which waqf
Chapter 5 | Circular-ESG Business Transformation and the Design of Islamic Financial Products
102–103 | Global Islamic Finance Report 2026
or philanthropic first-loss capital de-risks a commercial financing pool, while qard or concessional tranches fund audits, product redesign, cleaner equipment, water efficiency, repair tooling, or transition certification. Existing cash-waqf models for sustainable infrastructure and community development demonstrate that such layering is feasible rather than merely aspirational. A more ambitious version of the same idea reconceives the waqf itself.
A venture waqf is an incorporated endowment whose defining purpose is not general charity but making impactful, zero-waste halal enterprises successful and then exiting to recycle its support to the next cohort. Its signature instrument is equity-at-default: an interest-free loan or other Islamic debt contract that converts into a declining equity partnership if the enterprise defaults, rather than being secured by collateral and terminated by foreclosure. The financier thereby becomes a patient partner in distress instead of a liquidator, replacing the two foundational pillars of conventional lending—collateral at entry and foreclosure at exit—with compassion and shared ownership. For circular MSMEs, whose unconventional assets and longer payback periods make them precisely the borrowers that collateral-and-foreclosure lending rations out, equity-at-default removes the structural barrier directly and aligns the financier’s incentive with the survival of the enterprise rather than with the seizure of its assets.
Circular Takaful and Performance-Guarantee Protection
The sustainable-takaful literature shows that ESG and maqasid can be integrated into takaful through a disclosure-and-governance blueprint. Extending that logic, takaful should not merely insure against conventional risks; it can be designed to lower the cost of
Circular-ESG Business Transformation and the Design of Islamic Financial Products | Chapter 5
Global Islamic Finance Report 2026 | 103
circular operating models. One of the hidden barriers to repair, refurbishment, modular design, and reused-equipment systems is perceived performance uncertainty. Takaful can underwrite asset uptime, remanufactured-component performance, repair liability, or maintenance-contract fulfilment, and its underwriting criteria can be set to reward durability, traceability, training, occupational safety, and low-emission operation. So designed, takaful ceases to be a protective overlay and becomes an incentive mechanism for the regenerative quadrant—a way of pricing the reliability of circular systems so that they can compete with linear ones.
AWorkedApplication:FinancingGeothermalHeatPumping
Geothermal—or, more precisely, ground-source—heat pumping offers a near-ideal test of the framework because its difficulty is financial before it is technical. A ground-source system moves heat between a building and the stable temperature of the earth a few metres down, delivering both heating and cooling at a coefficient of performance several times that of combustion or electrical resistance, and the buried ground loop can last fifty years or more. At district scale, the University of Toronto's King's College Circle geoexchange—Canada's largest urban ground-source system, comprising 372 boreholes drilled 250 metres deep and completed in 2024—provides heating and cooling to more than thirty campus buildings while avoiding roughly 15,000 tonnes of carbon dioxide equivalent each year. At the residential scale, the Government of Ontario's Home Renovation Savings Program, delivered through Save on Energy and Enbridge Gas, offers homeowners rebates of up to CAD 12,000 toward a ground-source (geothermal) heat pump,
Chapter 5 | Circular-ESG Business Transformation and the Design of Islamic Financial Products
103 | Global Islamic Finance Report 2026
materially offsetting the front-loaded drilling cost that otherwise keeps the technology out of reach. Yet the asset is capital-heavy and front-loaded: most of its cost is drilling and excavation, incurred at the outset, while its value accrues slowly as avoided energy over decades. That profile is exactly the one that throughput-rewarding, collateral-and-foreclosure lending under-serves.
Geothermal heat pumping is therefore not merely an eligible green project; it is a worked case for whether Islamic contract design can carry a regenerative asset from aspiration to deployment. Efficiency alone places geothermal in Q4. A luxury villa or a commercial tower that sinks a borehole field becomes nature-positive—lower emissions, lower running cost—without necessarily widening access or touching the social axis; deployed only where capital is already abundant, it is technically circular and socially blind. The same asset class reaches Q1 only when the financing structure carries it there: when blended or waqf-backed arrangements extend it to households, mosques, schools, and small enterprises that the collateral system rations out, and when the contract rewards the fifty-year life of the loop rather than the next equipment sale. Two cautions from the framework apply directly. The system is an energy-regeneration case rather than a material-loop-closing one; it belongs to the regeneration of Nature through eco-efficient operation, not through narrowing material loops, and it should be described as such. And the rebound warning holds: cheaper comfort can induce additional consumption, so efficiency gains must be assessed at the level of the whole system rather than the single building.
Circular-ESG Business Transformation and the Design of Islamic Financial Products | Chapter 5
Global Islamic Finance Report 2026 | 103–104
Geothermal heat pumping is therefore not merely an eligible green project; it is a worked case for whether Islamic contract design can carry a regenerative asset from aspiration to deployment
Mapped against the five product families, geothermal assigns itself with unusual clarity. The servitised ijara facility is its natural primary structure. Because the ground loop is a long-lived asset whose entire value is its durability, a financier can retain ownership and charge for delivered heating and cooling—comfort as a service—rather than selling equipment outright. The building avoids the upfront drilling cost, while the financier, as owner, has every incentive to design for the fifty-year life, maintain the field, and recover residual value. An istisna' contract can sit ahead of the ijara to fund the custom drilling and installation, with the financier commissioning the borehole field under a construction contract and then leasing the completed system—the standard project-finance pairing for assets that must be built before they can be used.
The use-of-proceeds circular sukuk is the instrument of scale. A district system is precisely the kind of ring-fenced, asset-backed cash flow that an ijara sukuk securitises. The University of Toronto’s King’s College Circle geoexchange, completed in 2024 with 372 boreholes drilled 250 metres deep to heat and cool more than thirty campus buildings and to cut on the order of 15,000 tonnes of carbon
Chapter 5 | Circular-ESG Business Transformation and the Design of Islamic Financial Products
104 | Global Islamic Finance Report 2026
dioxide equivalent a year, is one such network. A GCC campus or villa-cluster system would present the same financeable profile. Geothermal falls squarely within the renewable-energy and efficiency categories already recognised as eligible use of proceeds in sustainable-sukuk practice, so the second-party opinion and impact-reporting machinery transfers without modification. It is the blended and waqf-based structures, however, that close the access gap and decide whether the technology ever leaves Q4. The barrier to household and small-enterprise geothermal is the front-loaded drilling cost set against a long payback. A blended structure in which a philanthropic or social-fund tranche underwrites the cost of funds turns an unbankable retrofit bankable, and equity-at-default removes the foreclosure cliff that makes lenders wary of borrowers whose principal asset is buried in the ground.
A venture waqf could itself own borehole fields serving lower-income neighbourhoods, schools, or mosques, leasing comfort at cost and recycling its capital to the next site—precisely the move that lifts geothermal out of premium-villa Q4 into community Q1. Circular takaful then underwrites the residual technical uncertainty that unsettles both lenders and owners: borehole-field performance, heat-pump uptime, and the long-term ground-temperature drift that can erode efficiency in heavily cooling-dominated fields when a loop is undersized or thermally unbalanced. By pricing that risk—and by rewarding the thermal-response testing and proper sizing that prevents it—takaful lets a fifty-year asset compete on level terms with a five-year air conditioner.
The case is strongest in the GCC, where the framework’s host context and the technology’s advantage coincide. Air conditioning consumes on the order of seventy per cent of electricity in Saudi
Circular-ESG Business Transformation and the Design of Islamic Financial Products | Chapter 5
Global Islamic Finance Report 2026 | 104
Arabia, and air-source units perform worst exactly when demand peaks, in air approaching 50°C, whereas the stable, cooler ground offers a far better heat sink. Peer-reviewed simulation for Riyadh finds ground-source systems delivering a higher coefficient of performance than air-source equivalents—about 4.1 against 3.8—with roughly a third lower annual energy use, against an eleven-year payback . That payback profile is itself the argument for patient, risk-sharing, socially subsidised Islamic capital rather than short-tenor commercial debt. Read through the coordinate system, geothermal heat pumping regenerates all three domains at once: Nature, through avoided combustion; the Economy, through an asset stewarded across half a century rather than churned; and Society—but only if the financing is deliberately designed to carry the technology beyond those who could already afford it. That conditional is the whole point of the framework.
Product innovation is insufficient unless it is embedded in transparent governance and credible impact reporting; otherwise the new instruments will simply reproduce the labelling problems of the linear-ESG quadrant in Islamic dress. The reporting standards point consistently in the same direction. ICMA guidance recommends annual allocation and impact reporting together with external review; the IFRS and EFRAG systems require disclosure of governance, strategy, risk management, and metrics; the Global Reporting Initiative (2021b) emphasises significant impacts on people and the environment; and the WB-IsDB (2025) report calls for a standardised Islamic climate-finance dashboard that tracks not
Chapter 5 | Circular-ESG Business Transformation and the Design of Islamic Financial Products
104–105 | Global Islamic Finance Report 2026
only financing volume but actual ESG performance and measurable mitigation and adaptation outcomes.
Taken together, these sources imply that a Circular-Maqasid-ESG product should carry at least four layers of measurement. Financial resilience covers cash-flow stability, movement in the cost of capital, and default or recovery outcomes. Circularity performance covers asset life extension, take-back rates, reuse and remanufacture volumes, recycled content, avoided waste, and resource productivity. Maqasid or social performance covers the inclusion of SMEs, affordability, job quality, worker safety, access to clean water and energy, and broader community benefit. Governance assurance covers Shari’a review, use-of-proceeds controls, impact assurance, and external second-party opinion or audit. These four layers correspond, not coincidentally, to the three regenerations defined earlier—of Economy, Nature, and Society— and held together by an assurance layer that keeps the other three honest.
Governance carries a particular burden here. The evidence that stronger Shari’a governance improves social and governance performance in Islamic banks without yet consistently improving environmental outcomes (is significant because it implies that governance quality alone is not enough: environmental performance depends on whether governance is actually attached to operational and contractual redesign. In practice, Shari’a boards, compliance functions, and internal Shari’a-audit processes should widen their attention from the permissibility of transaction form to the substance of transition design, treating durability, fair risk allocation, transparency of use of proceeds, and measurable public benefit as governance questions rather than peripheral sustainability topics. AAOIFI’s (2025) expanding governance architecture provides an
Circular-ESG Business Transformation and the Design of Islamic Financial Products | Chapter 5
Global Islamic Finance Report 2026 | 105
institutional basis for that move.
The practical implication for Islamic-finance jurisdictions is that circular product design and financial product design must be co-developed by ministries, standard setters, rating agencies, Shari’a boards, development banks, and industry associations working in concert
The policy conditions are equally demanding because regenerative products cannot scale in a vacuum. The WB-IsDB (2025) report recommends sector decarbonisation standards, taxonomies aligned with national policy and global standards, public-private pilot financing schemes, knowledge hubs, and centralised dashboards. European circular-economy policy offers parallel lessons on durability, reparability, digital product information, and the right to repair. These developments matter to finance because they reduce uncertainty over what counts as credible circularity, how assets should be tracked, and where performance data should come from. The practical implication for Islamic-finance jurisdictions is that circular product design and financial product design must be co-developed by ministries, standard setters, rating agencies, Shari’a boards, development banks, and industry associations working in concert. Four risks qualify the argument without overturning it.
Chapter 5 | Circular-ESG Business Transformation and the Design of Islamic Financial Products
105 | Global Islamic Finance Report 2026
Rebound effects mean that the savings from circular models can trigger additional consumption elsewhere, partially offsetting environmental gains. Measurement instability means that ESG ratings remain noisy and that divergence can distort incentives or license selective disclosure. Standard fragmentation means that the absence of common taxonomies and uneven capacity across jurisdictions continues to impede Islamic climate finance.
Moreover, substantive dilution means that a product can be labelled green, social, or Shari’a-compliant without demonstrably moving a firm toward durability, reparability, recovery, inclusion, or regeneration. These hazards do not invalidate the framework; they establish that governance and measurement are constitutive elements of the regenerative model rather than optional accessories. The argument carries its own limitations honestly. It is conceptual and design-oriented rather than empirical, and so it does not test the financial performance or risk characteristics of the proposed product families.
It draws on a literature that is stronger for sustainable sukuk and climate finance than for some other circular categories, particularly maintenance-linked Islamic finance and circular takaful. Because Islamic-finance jurisdictions differ in legal enforcement, tax treatment, governance centralisation, and disclosure maturity, the proposals here should be treated as adaptable archetypes rather than one-size-fits-all blueprints. Conceptual design work is nonetheless valuable at this stage because the literature itself repeatedly identifies the need for product innovation, standardised data systems, and ecosystem collaboration.
Circular-ESG Business Transformation and the Design of Islamic Financial Products | Chapter 5
Anchored by the coordinate system, this paper has argued that the strategic destination for Islamic sustainable finance is the regenerative quadrant, Q1, in which circular resource design, robust disclosure, stakeholder-centred materiality, and Shari’a-governed real-economy finance reinforce one another to regenerate Nature, Society, and the Economy at once. Read through the transformation engine of Dynamic Prescriptive Economics; the moves assembled here fall into three kinds—substitutions, transformations, and offsets (STOs)—and distinguishing among them clarifies which moves merely improve a linear business and which actually relocate it.
Most of the financial structures proposed here are substitutions: they re-form a contract so that the same economic function carries a different behavioural incentive. The servitised ijara substitutes leased performance for outright sale; equity-at-default substitutes a declining partnership for collateral and foreclosure; the blended murabaha substitutes concessional for commercial cost of funds; and circular takaful substitutes a durability-rewarding underwriting logic for conventional risk transfer. The use-of-proceeds circular sukuk, together with the allocation, impact, and disclosure machinery that accompanies it, belongs instead to the family of offsets: it ring-fences capital to eligible uses and accounts for benefit, compensating in one place for activity elsewhere. Substitutions and offsets are indispensable—they change incentives and direct capital—but neither, on its own, alters the underlying metabolism of the firm, which is precisely why a Shari’a-compliant, sukuk-funded, ESG-disclosing enterprise can still sit in the linear-ESG plateau of Q2.
Chapter 5 | Circular-ESG Business Transformation and the Design of Islamic Financial Products
106 | Global Islamic Finance Report 2026
The decisive category is transformation, and the paper has shown it at two depths. At the level of the asset, geothermal heat pumping is a genuine transformation: it replaces combustion with heat-moving, changing the production metabolism rather than the contract that finances it. But the largest transformation is of the business model itself—the relocation of the firm out of linear extraction (Q3), disclosure-led linear-ESG (Q2), and socially blind circularity (Q4) into the Circular-Maqasid-ESG form of Q1. This is the transformation that all the substitutions and offsets are ultimately in service of; absent it, they refine a linear enterprise without regenerating it. That ordering follows directly from the non-substitutability of the two axes. Because a gain on Nature cannot be traded for a loss on Society, and because mizan forbids transgression of the balance, offsets and substitutions cannot stand in for structural change: no amount of compensatory accounting or contractual reform can carry a firm across the quadrants while its business model remains linear. The central thesis is, therefore, both simple and demanding. The future of Islamic sustainable finance lies not in substituting and offsetting one's way to a slightly greener linearity but in financing the one transformation that matters—the transformation of the business model into a form that is structurally regenerative for Nature, Society, and the Economy alike.
AIDeclaration
The author used Anthropic's Claude, an AI language model, to assist with structural editing, prose refinement, reference formatting, and the verification of publicly available factual data during the preparation of this manuscript. All conceptual contributions, analytical arguments, and scholarly claims are the author's own, and
Circular-ESG Business Transformation and the Design of Islamic Financial Products | Chapter 5
Global Islamic Finance Report 2026 | 106
every AI-assisted output was reviewed, verified against primary sources, and edited by the author, who takes full responsibility for the content. No fabricated data, citations, or empirical results were generated or accepted in producing this work.
Chapter 5 | Circular-ESG Business Transformation and the Design of Islamic Financial Products
Conventional financial intermediation, driven by interest-bearing debt and speculative instruments, has proven inherently unstable, exacerbating inequality while divorcing finance from the real economy. This chapter critiques the rent-seeking logic of value-neutral finance and articulates an Islamic moral economy founded on risk-reward sharing, asset-backing, and social justice. It thus proposes a transformative alternative rooted in Islamic ethical finance, with waqf as its cornerstone. With the prohibition of interest, contractual/excessive uncertainty, and short-selling based speculative practices, it demonstrates how real-economy-anchored finance and waqf (the institution of Islamic endowments) offer a perpetual, welfare-oriented mechanism for financial intermediation that prioritises social inclusion along with the business in ethical perspective. Waqf, through its cash-based innovations and integration with FinTech and social sukuk, offers a sustainable mechanism for
financing public goods, micro-entrepreneurship, and climate resilience. This alignment offers a viable pathway toward an inclusive, welfare-oriented, and ethically grounded financial system that prioritises human dignity and planetary well-being over earning management/profit maximisation.
Keywords: Islamic ethical finance, social finance, value-based intermediation (VBI), SDGs, cash waqf, green sukūk, maqasid al-Shari’a, risk-reward sharing.
ThePrevalentValue-NeutralFinance
The global financial system stands at a critical juncture. Decades of debt-driven growth, speculative excess, and the treatment of money as a commodity have culminated in recurring crises, widening inequality, and ecological degradation. The structural flaws of this system are starkly evident in the recurring debt crises that have plagued the Global South. Historically, the collapse of Ottoman empire owing to the debt, and the role off Ottoman Public Debt Office (OPDA) in repaying that debt shows a red signal for such Islamic countries increasingly incurring debt despite the functioning of Islamic finance over the last few decades. In the modern era, the 2008 Global Financial Crisis, the 2023 collapse of Silicon Valley Bank, the sovereign debt traumas of Argentina and Greece, and the twin deficits of Islamic Republic of Pakistan are not discrete anomalies but symptoms of a deeply flawed and exploitative paradigm.
The human costs of this system are profound. Argentina's austerity-induced unemployment reached 25 per cent between 1998 and 2002, while Greece saw youth unemployment soar to 50 per cent during 2010–2015. These are the outcomes that violate Islam's
Waqf-based and Sustainability-aligned Model for Financial Intermediation – An Overview | Chapter 6
Global Islamic Finance Report 2026 | 113–116
Chapter Highlights
Figure 6.1: Mechanism of Waqf
Islamic Finance, VBI and the ESG
SDG 1 & 2: No Poverty, Zero Hunger
SDG 8: Decent Work and Economic Growth
SDG 13 & 15: Climate Action, Ecosystem Protection
Key Waqf Instruments
Cash Waqf Certificates (CWCs): Reflecting perpetual donations for welfare purposes, CWCs can equip banks and other waqf management institutions with tools to collect social savings and transform them into social capital.
Al-Khair Sukuk: These perpetual or time-bound instruments enable individuals to participate in social welfare initiatives, with proceeds deployed through qard al-Hasan, trading, or leasing for microbusinesses, small entrepreneurs, farmers, and SMEs.
Waqf-based Crowdfunding: This mechanism mobilises waqf and philanthropic resources from a broad base of contributors via online platforms, with models including donations, qard al-Hasan, rewards, credit-based structures, private equity, and sukuk.
Qard al-Hasan via Cash Waqf (QHCW): Recent studies have proposed sustainable personal financing models using cash waqf proceeds, presenting viable, Shari’a-compliant solutions to mitigate future economic crises.
Blockchain Integrated Waqf for transparent distribution
Rooted in divine accountability, risk-sharing, and the imperative of social justice, particularly the waqf-based intermediation offers a pathway to reclaim finance as a tool for human welfare and sustainability
Islamic social finance tools such as zakat and waqf can directly address SDGs 1 (poverty), 2 (hunger), 5 (gender equality), and 10 (reducing inequality), while sukuk can finance sustainable infrastructure (SDG-9)
Cash endowments historically financed artisans and small farmers on a risk-sharing basis, ensuring even the poorest access capital with dignity rather than debt servitude.
In Bursa, 20 per cent of cash waqfs survived over a century; Istanbul hosted 1,161 cash waqfs (46 per cent of total) between 1456 and 1551; and 761 operated in 18th-century Bursa. In 1954, surviving Ottoman cash waqfs were consolidated to form Türkiye’s Vakıflar Bankası, demonstrating the enduring institutional legacy of this model.
Waqf Applications for Environmental and Social Goals—A Part of the ESG
Today, waqf can be revitalised to address modern challenges in socio-economic sectors:
Education, Health & Housing: Waqf assets can fund schools, clinics, housing projects, and job creation programmes. In Malaysia, at least four universities maintain waqf endowments; IIUM alone funds 4,000 scholarships annually through waqf-generated income.
Environmental Protection: Waqf land can support reforestation, renewable energy, and eco-infrastructure. Examples include mangrove restoration in Indonesia, drought-resilient crops, water harvesting, and flood-prevention projects.
Clean Energy Access: Waqf-based microgrids and solar projects provide renewable energy to off-grid or disaster-prone communities.
Disaster Preparedness: Cash waqf can offer rapid relief, support community training, and improve resilience.
Urban Development: Green waqf spaces and eco-housing projects help reduce urban heat and flood risks.
Research & Innovation: Waqf can fund climate adaptation studies, Shari’a-compliant green finance instruments, and carbon offset initiatives.
prohibition of darar (harm) and the principle of maslaha (public good). The system allows capital to generate returns independent of real economic activity, while complex derivatives and short-selling enable speculation by trading in risk itself. It thus operates on a logic that permits profit without productive contribution.
It is against this backdrop that Islamic ethical finance emerges as a principled and practical alternative. Equitable distribution of income is central to the ethical vision of Islamic economics and finance, which aims at achieving socio-economic justice. By integrating waqf with businesses oriented financial instruments, technology, and sustainability frameworks, Islamic finance can reclaim its original purpose: promoting justice, shared prosperity, and environmental stewardship. Rooted in divine accountability, risk-sharing, and the imperative of social justice, particularly the waqf-based intermediation offers a pathway to reclaim finance as a tool for human welfare and sustainability. It insists that finance must serve society, not exploit it, and provides sustainable funding for entrepreneurial finance at micro level and social development.
Rooted in divine accountability, risk-sharing, and the imperative of social justice, the waqf-based intermediation offers a pathway to reclaim finance as a tool for human welfare and sustainability
Chapter 6 | Waqf-based and Sustainability-aligned Model for Financial Intermediation – An Overview
116 | Global Islamic Finance Report 2026
However, over the past five decades of Islamising banking, little effort has been made to connect the growth of Islamic finance, including sukuk, with the issues of injustice and inequality. For Islamic finance to fulfil its promise, it must go beyond legal forms and embrace the spirit of justice and inclusion. This chapter proposes Islamic ethical finance as a universal model capable of transforming global finance into a system that promotes shared prosperity, human dignity, and planetary stewardship.
TheEthicalFoundationsofIslamicFinance
At the heart of Islamic finance lies a fundamental ethical proposition: earning a return without contributing to real economic activity, without taking business risk and creating value, is deemed unethical and prohibited. The Islamic moral economy insists that profits must be tied to productive enterprise, real assets, and mutual consent, with risk and reward shared equitably among transacting parties.
Conventional finance treats money as a commodity to be bought, sold, or rented. Islamic finance, by contrast, views money as a medium of exchange, not a source of independent profit. It rejects the capitalist logic of "money earning money" through interest, short selling, and speculative derivatives as morally untenable and economically destabilising. Risk and reward must be shared equitably among transacting parties. This principle rejects one of the most damaging dynamics of the global financial order: the unaccountable accumulation of wealth through debt and financial engineering, often at the expense of the poor, the uninformed, and future generations. Islamic finance promotes non-debt markets or interest-free debt markets rooted in real sector activities. Household
Waqf-based and Sustainability-aligned Model for Financial Intermediation – An Overview | Chapter 6
Global Islamic Finance Report 2026 | 116
savings, usually held in liquid form, are mobilised into investment either via leasing of capital goods or risk-based financing structures aligned with Shari’a principles.
Equity and efficiency are closely tied to environmental concerns and climate resilience, which are central to the UNDP’s SDG 2030 agenda. Sustainability is critical for IsDB’s member countries, especially in Asia and Sub-Saharan Africa, where climate risks like floods, storms, and droughts threaten lives, food security, health, and economic stability. The poorest and most vulnerable are often the most affected.
Self-Discipline, Social Justice, and Accountability
Islamic finance builds a framework of internal moral discipline supported by external legal prohibitions. The transformative potential of Islamic finance lies in its orientations with the higher objectives of Islamic law. These objectives (maqasid) encompass the protection of faith, life, intellect, lineage, and property, and extend to the promotion of justice, equity, and human welfare. At the societal level, institutions must uphold justice, fair dealings, disclosure, and accountability.
The ethical system encompasses contractual obligations, requiring clarity in terms, transparency in pricing, and full disclosure of risk and liability. Prohibitions on deceptive practices and the emphasis on mutual benefit aim to foster trust-based economies that prioritise long-term stability over short-term gain.
The alignment between maqasid and global sustainability frameworks is being recognised increasingly. Studies have found that most of the 17 Sustainable Development Goals comfortably match
Chapter 6 | Waqf-based and Sustainability-aligned Model for Financial Intermediation – An Overview
116–117 | Global Islamic Finance Report 2026
with the long-term objectives of Shari’a, presenting significant scope for waqf stakeholders to develop development plans aligned with the SDG framework. Islamic social finance tools such as zakat and waqf can directly address SDGs 1 (poverty), 2 (hunger), 5 (gender equality), and 10 (reducing inequality), while sukuk can finance sustainable infrastructure (SDG-9).
The Trap of Interest and the Debt Slavery
At the core of the conventional system is interest-bearing debt, used by individuals, corporations, and sovereign states to finance consumption, growth and investment. Financial liberalisation opened the door to increasingly complex and opaque instruments that derive profit from trading in risk itself.
This model rewards the possession of (financial) capital while penalising those who need access to it, especially the poor, leading to the slavery of nations having little discretion on preparing and implementing any reform policies. For ensuring repayments of funds, production and services, sectors are taxed increasingly, weakening the export competitiveness and deteriorating exchange rate.
Stiglitz (2003) meticulously documents how IMF-imposed so-called austerity in Argentina (1998–2002) and Greece (2010– 2015) prioritised creditor repayments over public welfare, leading to catastrophic social consequences. In Argentina, austerity triggered a 25 per cent unemployment rate and healthcare collapse, while Greece saw youth unemployment soar to 50 per cent—violating Islam's prohibition of darar (harm) and the principle of maslaha (public good).
Islamic finance, on the other hand, necessitates real asset backing,
Waqf-based and Sustainability-aligned Model for Financial Intermediation – An Overview | Chapter 6
Global Islamic Finance Report 2026 | 117
actual ownership, and contractual clarity, the safeguards that mitigate systemic risk and promote long-term economic stability.
It thus provides an ethical foundation for financial intermediation by ensuring a proper linkage between the economy and finance, leading to shared growth and equitable distribution of income.
Chapter 6 | Waqf-based and Sustainability-aligned Model for Financial Intermediation – An Overview
The ethical architecture of finance aligns with nature and the natural disposition of human beings and aims to uphold the dignity, freedom, and moral agency of individuals within a just economic order. Accordingly, ethical exchange system covers all categories of contract like partnerships, sales and leases that human beings may genuinely need for conduct of economic activities. It is crucial to clarify that the inequality-reducing potential of Islamic finance is not confined to equity-based partnerships (mudaraba, musharaka) but extends across the entire spectrum of permissible contracts, also including trade-based (murabaha, salam, istisna'a) and lease-based (ijara) modes. All these instruments, when implemented authentically, involve genuine risk-reward sharing based on economic activity and value addition, fundamentally distinguishing them from conventional debt. In the conventional interest-based finance an increasing number of investors add to their wealth without creating real goods and services for economy, thus creating a bias against commodity-producing sectors. The result is a self-reinforcing cycle of wealth concentration, as documented through IMF austerity programmes that harmed export competitiveness and devastated health and education in indebted nations, through microfinance schemes that trapped the poor in cycles of over-indebtedness.
Risk-reward sharing operates differently across modes as per Islamic law of contracts, yet each embeds real economic risk and value creation. Mudaraba and musharaka align returns directly with business profitability, enabling capital-deficient entrepreneurs to access funding, with the financier bearing full downside
Waqf-based and Sustainability-aligned Model for Financial Intermediation – An Overview | Chapter 6
Global Islamic Finance Report 2026 | 118
risk. Salam provides advance payment to producers of goods with regular markets, particularly farmers, who typically lack working capital, addressing rural poverty by stabilising agricultural incomes and preventing exploitation by money lenders. Ijara transfers only the usufruct of an asset while ownership and all related liabilities remain with the lessor, facilitating asset formation for small enterprises without incurring debt burdens. Murabaha involves genuine trade wherein the financier purchases goods, assumes ownership and risk until delivery, and earns profit through value-added commerce, supporting supply chains and SME access to essential goods. Istisna'a enables project-based financing for infrastructure and customised production, supporting long-term capital formation and employment in manufacturing sectors. Similarly, ju'ala can finance services, innovations and wealth creating activities for which ijara might not be feasible. Ju'ala deals with output uncertainty by linking payment to the realisation of a defined result or service.
The above contracts tackle wealth inequality through diverse, non-predatory access for farmers, entrepreneurs, and businesses. They anchor finance to the real economy, curbing financialisation, and generate returns through value addition and risk-sharing rather than time preference, ensuring wealth circulation over hoarding. Further, risk-reward sharing model can also be integrated with Islamic social finance especially zakat, waqf, qard al-hasan, to create a comprehensive anti-inequality framework. Cash endowments historically financed artisans and small farmers on a risk-sharing basis, ensuring even the poorest access capital with dignity rather than debt servitude. In this chapter, of course, we shall be discussing the institution of waqf only. However, the transformative potential of risk-reward sharing and social finance requires
Chapter 6 | Waqf-based and Sustainability-aligned Model for Financial Intermediation – An Overview
118 | Global Islamic Finance Report 2026
governance frameworks that enforce substantive compliance, ensure equitable profit distribution, and financing to underserved sectors. When implemented authentically, the comprehensive framework of Islamic finance, spanning equity, trade, and lease contracts, offers a structural alternative to conventional debt, systematically reversing the wealth concentration inherent in interest-based systems.
Cash endowments historically financed artisans and small farmers on a risk-sharing basis, ensuring even the poorest access capital with dignity rather than debt servitude
The Social Finance Framework
Islamic social finance comprises especially zakat and waqf, Islamic microfinance, and cooperative takaful. These instruments encourage the common people in general and the wealthy in particular to act responsibly for societal well-being. While waqf is an optional category of philanthropy seeking Allah’s blessings, zakat, a compulsory levy on the wealthy, serves as a systemic mechanism for wealth redistribution, ensuring that a portion of the income and wealth of the relatively rich is passed on to those who lack sufficient resources for survival. This enhances financial and social inclusion, boosts overall economic growth, and promotes countercyclical economic policy.
Waqf-based and Sustainability-aligned Model for Financial Intermediation – An Overview | Chapter 6
Global Islamic Finance Report 2026 | 118–119
While takaful is a mechanism for mutual indemnification of losses among the members of a group, qard al-hasan (benevolent loan) is an interest-free loan extended to those in need, with repayment of the principal only. It represents the highest form of charitable financing, enabling entrepreneurs, farmers, and families to meet their needs without falling into debt traps. Islamic financial institutions, particularly the waqfs, can integrate qard al-hasan into their portfolios as a core social finance instrument.
Unlike secular ESG frameworks that rely on incentives and market preferences, Islamic finance anchors sustainability in divine accountability. It offers a moral foundation for addressing poverty, inequality, and environmental degradation. The tools of Islamic social finance are not peripheral; they are foundational to the Islamic economic framework.
Waqf as an institution of social welfare preceded the modern institution of ‘TRUST’. The West learned about waqf as charitable endowments during the Crusades
The Emergence of VBI
In the wake of the 2008 Global Financial Crisis, Value-Based Intermediation (VBI) emerged in global finance. VBI tends to create an environment where social, sustainability, and governance
Chapter 6 | Waqf-based and Sustainability-aligned Model for Financial Intermediation – An Overview
119 | Global Islamic Finance Report 2026
aspects and the SDGs could be better served. The key findings of the WB-IDB report (2016) for promoting Islamic finance for shared prosperity include implementing a sound regulatory framework, harmonising Shari’a standards, and developing suitable mechanisms for Islamic financial products.
VBI may involve:
Social Finance: Investments/offerings having social impact, development of research and education investments that play a role in assisting the poor, needy, and indebted individuals.
Development-based Investments: Offerings having significant growth potential in an economy, infrastructure, micro businesses, or SMEs; and
Environment-friendly Investments: Investments that help in protecting the environment.
Islamic Finance and the Current ESG Framework
Islamic finance naturally supports the United Nations' Sustainable Development Goals. The World Bank-Islamic Development Bank Report (2016) and subsequent IFDR analyses have documented this alignment:
SDG 1 & 2 (No Poverty, Zero Hunger): Through zakat, waqf, and inclusive finance
SDG 8 (Decent Work and Economic Growth): Via real-economy-linked investments
SDG 13 & 15 (Climate Action, Ecosystem Protection): Through ethical investment screening and green sukuk
Waqf-based and Sustainability-aligned Model for Financial Intermediation – An Overview | Chapter 6
Global Islamic Finance Report 2026 | 119
The current ESG frameworks operate at global level within the same interest-based, speculative financial logic that generates the inequalities and instabilities they ostensibly address. They do not challenge the structural primacy of shareholder value; they merely ask corporations to consider additional variables in their profit calculations. This creates inherent instability: when economic pressures intensify, ESG commitments are easily abandoned, as witnessed during recent inflationary periods when sustainability pledges were quietly shelved. Moreover, ESG lacks a coherent philosophical foundation—what constitutes "social" or "governance" varies across jurisdictions, industries, and rating agencies, producing confusion rather than genuine transformation. Justice-centred finance provides a fundamentally different anchor because it rests on divinely mandated principles rather than any corporate discretion. The higher objectives of Shari’a operationalise justice through explicit prohibitions on exploitative practices: riba (interest), which institutionalises unearned returns and debt-slavery; gharar (contractual uncertainty), which enables exploitation through asymmetric information and earnings without business risk; and maysir (gambling/speculation), which detaches finance from productive enterprise. These are not aspirational guidelines but legally enforceable constraints, embedded in contract law and institutional governance.
I. Waqf as an Institution for Financial and Social intermediation
As a unique institution of the Islamic economy, waqf facilitates intergroup resource sharing to address both short-term consumption needs and long-term productive requirements. It enhances financial and social inclusion, boosting overall economic growth by
Chapter 6 | Waqf-based and Sustainability-aligned Model for Financial Intermediation – An Overview
119–120 | Global Islamic Finance Report 2026
helping the poor maintain their human capital and by promoting countercyclical economic policy. Historically, waqf has financed public infrastructure such as schools, hospitals, and water systems. Real estate was the primary form in the early Islamic era. Later on, movable, financial, and intangible assets were included to facilitate cash endowments. Its scope extended from fulfilling the basic needs of the members of a society to enabling entrepreneurs in the MSME sector.
Waqf as an institution of social welfare preceded the modern institution of ‘TRUST’. The West learned about waqf as charitable endowments during the Crusades. However, only the 20th-century ‘welfare states’ popularised this trend of waqf-like institutions in their quest for mitigating the impact of the capitalistic economy in terms of widening the gap between the poor and the rich. The historical record demonstrates the transformative potential of waqf. In finance perspective, cash waqfs functioned as proto-banking institutions facilitating capital distribution among small farmers and consumers. The OIC Fiqh Academy (2004), as well as AAOIFI (Shari’a Standard # 60 on waqf), provide for waqf in the form of cash and other liquid assets. Unlike conventional banks, where capital is pooled from multiple depositors and interest is paid to capital owners, cash waqfs relied on single-capital endowments with zero cost of capital. Profits were thus entirely channelled to social and charitable purposes. Beneficiaries were predominantly small consumers rather than entrepreneurs, underscoring the redistributive role of these institutions.
Waqf-based and Sustainability-aligned Model for Financial Intermediation – An Overview | Chapter 6
Global Islamic Finance Report 2026 | 120
In 1954, surviving Ottoman cash waqfs were consolidated to form Türkiye's Vakıflar Bankası, demonstrating the enduring institutional legacy of this model
Cash waqf originated as an Ottoman innovation in the 15th century and provided small loans to agricultural and urban guilds, pooling resources to meet community needs. During the Ottoman era, cash waqfs played a pivotal role in financing education, health, and infrastructure, reducing public borrowing and stabilising interest rates. In Bursa, 20 per cent of cash waqfs survived over a century; Istanbul hosted 1,161 cash waqfs (46 per cent of total) between 1456 and 1551; and 761 operated in 18th-century Bursa. In 1954, surviving Ottoman cash waqfs were consolidated to form Türkiye's Vakıflar Bankası, demonstrating the enduring institutional legacy of this model.
II. Modern Innovations: Cash Waqf Models
Contemporary scholarship has identified six models of cash waqf implementation: waqf shares schemes, deposit cash waqf, compulsory cash waqf, corporate waqf, deposit product waqf, and co-operative waqf. These models are now implemented across diverse regions, from Malaysia and Indonesia to Singapore, Bahrain, South Africa, and Uzbekistan. Digitalisation of finance and FinTech are serving as tools for efficient functioning of waqf system. Through
Chapter 6 | Waqf-based and Sustainability-aligned Model for Financial Intermediation – An Overview
120 | Global Islamic Finance Report 2026
its very nature, Islamic FinTech cares for the elements of the environment, social values, and corporate governance (ESG) as well. The alignment of certain Islamic financial products and environmental, social, and governance factors along with recent strides in digitalisation may allow Islamic FinTech to make a strong foothold in the market. FinTech enables Shari’a-compliant mechanisms for collecting, investing, and channelling funds toward public welfare while reducing fraud and expanding financial inclusion. Key innovations include:
Blockchain: Enables transparency in waqf and zakat distribution.
Smart Contracts: Automate ethical compliance in murabaha and ijara contracts.
Digital Islamic Banks: Extend reach to unbanked populations through inclusive and mobile-friendly Shari’a-compliant services.
Crowdfunding Platforms: Enable entrepreneurs to present objectives and business plans, attracting direct funding without conventional intermediaries.
Waqf foundations, being among financial service providers, must rise to the occasion of the fourth industrial revolution, which is shaping the economy through innovations enabling easy access to internet services for all.
Waqf-based and Sustainability-aligned Model for Financial Intermediation – An Overview | Chapter 6
Global Islamic Finance Report 2026 | 120–121
A viable alternative to interest-based microcredit programmes is social-cum-business finance based on waqf, benevolence, and equitable risk-and-reward sharing
III. Waqf Applications for Environmental and Social Goals—A Part of the ESG
Today, waqf can be revitalised to address modern challenges in socio-economic sectors:
Education, Health & Housing: Waqf assets can fund schools, clinics, housing projects, and job creation programmes. In Malaysia, at least four universities maintain waqf endowments; IIUM alone funds 4,000 scholarships annually through waqf-generated income.
Environmental Protection: Waqf land can support reforestation, renewable energy, and eco-infrastructure. Examples include mangrove restoration in Indonesia, drought-resilient crops, water harvesting, and flood-prevention projects.
Clean Energy Access: Waqf-based microgrids and solar projects provide renewable energy to off-grid or disaster-prone communities.
Disaster Preparedness: Cash waqf can offer rapid relief, support community training, and improve resilience.
Chapter 6 | Waqf-based and Sustainability-aligned Model for Financial Intermediation – An Overview
121 | Global Islamic Finance Report 2026
Urban Development: Green waqf spaces and eco-housing projects help reduce urban heat and flood risks.
Research & Innovation: Waqf can fund climate adaptation studies, Shari’a-compliant green finance instruments, and carbon offset initiatives.
a) Financial Intermediation for Social Inclusion
Financial intermediation aimed at social inclusion goes beyond expanding formal banking networks. Its ultimate goal is not merely financial inclusion but social inclusion—ensuring full and fair access to collective resources and activities; the maintenance of social relationships with family, friends and acquaintances; and the development of a sense of group belonging. Achieving this requires a value-based, just, equitable, and benevolent financial system capable of addressing the paradox of scarcity amidst abundance. The shortcomings of conventional microfinance underscore this need. Stewart et al. in their paper, published in 2010, found that some interest-based microcredit programmes worsened poverty, with borrowers often withdrawing children from school when businesses failed to generate sufficient profit to meet high interest costs. Sinclair in the paper published in 2012 similarly argued for reconstructing microfinance systems to prevent such failures. The deeper flaw lies in interest-based debt structures that prioritise lender profits rather than resolving entrenched social challenges. A viable alternative is social-cum-business finance based on waqf, benevolence, and equitable risk-and-reward sharing. Institutions in the "third sector," such as waqf, are uniquely positioned to provide interest-free loans because their mission and objectives prioritise collective welfare over profit.
Waqf-based and Sustainability-aligned Model for Financial Intermediation – An Overview | Chapter 6
Global Islamic Finance Report 2026 | 121
b) Institutional Models and Instruments
Islamic ethical finance institutions—both banking and non-banking entities—can play a pivotal role in integrating financial and social intermediation. The institution of waqf, encompassing both fixed and liquid assets, provides a sustainable funding base for diverse socio-economic activities.
Key waqf-based instruments include:
Cash Waqf Certificates (CWCs): Reflecting perpetual donations for welfare purposes, CWCs can equip banks and other waqf management institutions with tools to collect social savings and transform them into social capital.
Al-Khair Sukuk: These perpetual or time-bound instruments enable individuals to participate in social welfare initiatives, with proceeds deployed through qard al-hasan, trading, or leasing for microbusinesses, small entrepreneurs, farmers, and SMEs.
Waqf-based Crowdfunding: This mechanism mobilises waqf and philanthropic resources from a broad base of contributors via online platforms, with models including donations, qard al-Hasan, rewards, credit-based structures, private equity, and sukuk.
Qard al-hasan via Cash Waqf (QHCW): Recent studies have proposed sustainable personal financing models using cash waqf proceeds, presenting viable, Shari’a-compliant solutions to mitigate future economic crises.
Chapter 6 | Waqf-based and Sustainability-aligned Model for Financial Intermediation – An Overview
121–122 | Global Islamic Finance Report 2026
c) Contemporary Applications of Waqf for Social Finance
Malaysia has emerged as a leader in waqf-based innovation. In April 2024, the Securities Commission Malaysia signed a Memorandum of Understanding with the IsDB Group to enhance cooperation in the Islamic capital market and expand Islamic FinTech and social finance, particularly waqf. In Indonesia, Cash Waqf Linked Sukuk (CWLS) models have been developed to support economic and social initiatives, with waqf funds used to enhance the national economy and promote Islamic banking. The integration of waqf with green financing, such as green sukuk, bridges ethical imperatives with sustainable development.
d) Green Sukuk and Climate Finance
Green sukuk are designed to fund environmentally beneficial projects while adhering to Shari’a principles. Since the inaugural issuance of a US$58 million green sukuk in July 2017, these instruments have expanded across OIC member countries. Green sukuk supports renewable energy, energy efficiency, sustainable transportation, waste management, and climate resilience. Unlike conventional green bonds, green sukuk are underpinned by tangible assets, providing a unique layer of risk mitigation and investor confidence. The World Bank's November 2025 report, "From Green Sukuk Innovation to Greener Halal Value Chains," documents how Islamic finance has grown from US$17.8 billion in 2017 to US$82.3 billion, a compound annual growth rate of 24.4 per cent. Pakistan issued its inaugural sovereign domestic Green Sukuk—a 3-year, PKR30 billion (US$106 million) instrument—in 2025. Malaysia broke ground with the world's first renminbi-denominated climate sukuk in October 2025, representing a new generation of
Waqf-based and Sustainability-aligned Model for Financial Intermediation – An Overview | Chapter 6
Global Islamic Finance Report 2026 | 122
Shari’a-compliant instruments aligned with government sustainability priorities.
Product design should shift toward genuinely asset-based and inclusive instruments, including musharaka for SMEs, integrated waqf-zakat platforms, and green sukuk
Challenges,Gaps,andthePathForward
The ethical realisation of Islamic finance faces several challenges. Regulatory dualism ties institutions to conventional interest-based benchmarks like LIBOR, while limited awareness and capacity lead to the replication of familiar, conventional products. Profit maximisation pressures drive short-termism and neglect of social instruments such as qard al-hasan and waqf, while "Shari’a-washing”-seeking lenient opinions to justify form over substance-further erodes ethical integrity. Addressing these gaps demands a coordinated strategy. Shari’a governance must prioritise ethical substance through maqasid-based evaluations and reject mimicry. Product design should shift towards genuinely asset-based and inclusive instruments, including musharaka for SMEs, integrated waqf-zakat platforms, and green sukuk. Capacity building is crucial, embedding ethical reasoning and maqasid frameworks into education and professional training. Supporting ecosystems, including ethical
Chapter 6 | Waqf-based and Sustainability-aligned Model for Financial Intermediation – An Overview
122 | Global Islamic Finance Report 2026
rating agencies, FinTech platforms, and social venture incubators, are equally necessary. Finally, technological innovation must be embraced with integrity, ensuring that digital tools advance justice and shared welfare rather than merely replicating exploitative patterns. Through these coordinated efforts, Islamic finance can bridge its theory-practice divide and fulfil its promise as a truly ethical and sustainable financial system.
TowardsanEthicalFinanceCivilisation
History reveals the inherent instability of debt-driven financial systems, as demonstrated by crises from Latin America in the 1990s to the 2008 global meltdown and the 2023 collapse of Silicon Valley Bank. These recurring failures expose the dangers of excessive leverage and speculation, underscoring the resilience of Islamic finance, which emphasises risk-sharing and tangible asset backing. This system, rooted in ethical principles common to all major faiths and civilised cultures, champions justice, equity, and shared welfare, inherently aligning with the UN’s SDGs by promoting efficiency alongside social justice. Achieving this balance requires reorganising financial systems according to divine moral codes, which provide a blueprint for equality, human dignity, and accountability. Human limitations in foresight necessitate reliance on such guidance, as the Qur’anic narratives remind us. Central to this vision is the institution of waqf, a civil framework with deep historical roots. Its revival requires a legal structure that grants founders autonomy over objectives and management within Shari’a boundaries, while ensuring transparency and robust governance.
Bridging theory and practice in Islamic finance is not merely a technical reform but a civilisational project aimed at restoring trust
Waqf-based and Sustainability-aligned Model for Financial Intermediation – An Overview | Chapter 6
Global Islamic Finance Report 2026 | 122–123
in financial relationships and embedding welfare and justice at the heart of economic policy. This demands a clear clarification of value-based and ethical investments to categorically exclude interest, short-selling, and speculation. Currently, regulators and Islamic banks often fall short, operating on conventional profit-maximisation models. A new regulatory framework is essential to enforce moral and business ethics, moving beyond financial inclusion towards genuine social inclusion where all members of society benefit from shared prosperity.
Technology, particularly FinTech and crowdfunding, can significantly expand waqf’s role by facilitating micro-level participation and efficient fund distribution, though success is subject to the sound legal, Shari’a, and regulatory frameworks. To unlock this potential, waqf must be integrated into key economic growth activities alongside Islamic finance and the digital economy, creating an inclusive ecosystem involving banks, asset managers, FinTech start-ups, and regulators. Malaysia’s Shared Prosperity Vision 2030 and its progressive FinTech regulations offer instructive examples. Furthermore, linking corporate social responsibility funds, especially from financial institutions, to waqf-based community development can be instrumental in enhancing socio-economic welfare. Waqfs can finance micro-businesses, capacity building, and public social welfare, thus functioning as both direct and indirect financial intermediaries, alleviating government burdens tied to budgetary deficits. Consequently, waqf legislation should not only simplify philanthropy but also encourage broad participation in wealth-sharing.
Guided by ihsan, or excellence in conduct, Islamic finance can fulfil its promise of fostering inclusive and sustainable growth. By
Chapter 6 | Waqf-based and Sustainability-aligned Model for Financial Intermediation – An Overview
123 | Global Islamic Finance Report 2026
embracing such conduct, it can set a global benchmark for ethical finance. This is particularly relevant given the vast opportunities in financing the global transition to a low-carbon future, which demands a decisive shift from fossil fuels to renewables. Developing economies require new policies for macroeconomic resilience and technological adoption. A waqf-based financial architecture anchored in mission clarity and accountability can drive green finance, micro-entrepreneurship, and ethical capital markets, ultimately building a caring society rooted in peace and shared prosperity.
Waqf-based and Sustainability-aligned Model for Financial Intermediation – An Overview | Chapter 6
The financial-services landscape is undergoing a significant transformation through the convergence of Next-Generation Artificial Intelligence and Financial Technology. Traditional intermediaries such as commercial banks and investment institutions have long played a vital role in channelling surplus capital to productive opportunities through centralised, largely manual, and historically data-driven processes. AI-driven FinTech solutions, however, are challenging this model by enabling real-time asset allocation, instant credit-risk analysis using alternative data, and tailored financial products that reduce transaction costs and boost efficiency.
The purpose of this chapter is to explore the effects of these technologies on traditional financial intermediation, with particular focus on their potential contribution to socially responsible, maqasid al-Shari’a-aligned Islamic finance. AI-led systems can create unparalleled opportunities for financial inclusion, risk mitigation through proactive fraud detection, and the structuring of innovative Shari’a-compliant products, including intelligent sukuk structuring and ethical takaful models, but they also present significant challenges. These include cyber-security exposures, data-privacy
concerns, algorithmic bias, and the misalignment of borderless digital transactions with current regulatory and taxation regimes. This study contends that Next-Gen AI-FinTech can be a transformative force for building ethical financial systems centred on human welfare, the fair distribution of resources, and sustainable growth, in keeping with the theme of GIFR 2026, “Social Responsibility Driven Financial Intermediation – Innovative and Technological Pathways to Maqasid-aligned Transformations.” By embedding these principles into AI architectures, Islamic financial institutions can chart a responsible digital transformation that keeps the financial system fair, transparent, and socially beneficial.
The chapter concludes with strategic recommendations for regulators, Islamic banks, and FinTech innovators to harness these tools while upholding ethical standards, helping to build a more inclusive and resilient Islamic finance ecosystem projected to exceed US$6 trillion by the end of 2026.
Financial intermediation is the essence of modern economies. It is the mechanism through which the surplus funds of saving units are transferred to borrowing units, reducing information asymmetry and managing risk. Traditional intermediaries such as commercial banks, investment firms, and mutual funds have relied on centralised organisational models, largely manual underwriting, and historical credit records. Over the decades, these institutions have played a key role in providing financial stability and supporting economic growth. The financial world is now changing dramatically as a result of the convergence of Next-Generation Artificial Intelligence and Financial Technology (FinTech). The intermediation function is being reshaped by advanced technologies including deep learning, natural language processing (NLP), generative AI,
and predictive analytics. The capacity of AI to optimise asset allocation in real time, to make instant credit decisions based on alternative data, and to create highly personalised financial products lowers the transaction costs and operational inefficiencies associated with legacy systems.
This technological inflection arrives at a pivotal moment for the global Islamic finance industry. By the end of 2026, total assets of the sector are projected to exceed the US$6 trillion mark, with double-digit growth and increasing mainstream penetration. Islamic finance has moved from a specialist niche to an integral part of the world’s financial architecture, and it is now positioned to lead responsible innovation. This chapter examines how Next-Gen AI-powered FinTech is affecting contemporary modes of financial intermediation, and specifically how it aligns with the concept of maqasid al-Shari’a. The three research objectives are: (1) to examine the efficiency, security, and structural impact of these technologies; (2) to analyse their potential for promoting socially responsible financial intermediation; and (3) to outline pathways for embedding the Shari’a objectives of justice, equity, and public welfare (maslaha) within AI-FinTech ecosystems. To accomplish these aims, the chapter begins with a review of the relevant theory and literature. It then explores the technological transformation, the accompanying gains in efficiency, the security and ethical issues that arise, and the maqasid al-Shari’a perspective. Lessons from global practice, regulatory and taxation considerations, and strategic recommendations follow, concluding with a forward-looking synthesis.
TheoreticalFoundation&LiteratureReview
This chapter is grounded in established theories of financial
Industry reports document digital sukuk, AI-driven takaful models, and Blockchain-based waqf platforms, all of which are positioned to improve financial inclusion while ensuring compliance.
Table 11.1: Traditional vs. AI-Driven Financial Intermediation
Aspect
Traditional Model
AI-Driven FinTech Model
Structure
Centralised, hierarchical
Decentralised / hybrid networks
Decision-making
Manual, relationship-based
Real-time, data-driven, algorithmic
Data sources
Historical financial data
Alternative + unstructured big data
Transaction speed
Days (settlement delays)
Seconds to instantaneous
Cost structure
High overhead (branches, staff)
Significantly lower marginal costs
Risk assessment
Static credit scoring
Dynamic, predictive AI models
Customer access
Limited by geography & documentation
Borderless, inclusive (thin-file borrowers)
Governance
Regulatory compliance & human oversight
Algorithmic + smart-contract automation
Source: Adapted from Aldasoro et al. (2025) and Philippon (2016).
Traditional versus AI-driven Intermediation
Traditional financial intermediation operates through a centralised set-up in which intermediaries undertake delegated monitoring, liquidity provision, and risk transformation. By contrast, AI-based models harness large volumes of data and computational power to automate and optimise these functions. The key differences are summarised in Table 11.1.
Operational Efficiency in Islamic Banks: Illustrative Examples
A number of Islamic banks are already realising substantial benefits. CIMB Islamic Bank (Malaysia) and Al Rajhi Bank (Saudi Arabia) have applied AI to accelerate credit decisioning and customer onboarding, with the former reporting loan processing up to 70 per cent faster. Dubai Islamic Bank has deployed AI-driven anti-money-laundering (AML) solutions that reduced false-positive rates by more than 50 per cent, freeing compliance teams in the UAE to focus on higher-value activities. Bank Syariah Indonesia (BSI) has integrated AI chatbots and predictive analytics to improve customer engagement and reduce operational costs. These examples show that AI adoption in Islamic banking can deliver both cost savings and a competitive edge relative to conventional banks and conventional FinTech offerings.
Table 11.2: Traditional vs. AI-driven Financial Intermediation
Institution
Module/Component
Benefits
CIMB Islamic Bank (Malaysia)
Credit Decisioning and Customer Onboarding
Loan processing up to 70 per cent faster
Al Rajhi Bank (Saudi Arabia)
Credit Decisioning and Customer Onboarding
--
Dubai Islamic Bank
AI-driven Anti-Money-Laundering (AML)
Reduction in false-positive rates by more than 50 per cent
Bank Syariah Indonesia (BSI)
Customer Engagement
AI Chatbots, Predictive Analytics
Reduction in operational costs
intermediation, disruptive innovation, and the ethical framework of Islamic finance.
Financial intermediation theory holds that intermediaries such as banks exist to reduce information asymmetry, transaction costs, and risk between savers and borrowers. Diamond (1984) is seminal in arguing that economies of scale in monitoring borrowers improve overall economic efficiency through delegated monitoring. Allen and Santomero (1997) later emphasised the role of intermediaries in risk management and in providing liquidity within increasingly complex markets. These classical theories, however, were built for a pre-digital world and must be reconsidered in a technologically disrupted environment.
The theory of disruptive innovation is especially well-suited to explaining how FinTech and AI are being integrated into finance. AI-based platforms initially target under-served markets with simpler, cheaper offerings, such as peer-to-peer lending platforms and robo-advisory services — before gradually moving up the value chain and eventually challenging incumbents. Machine learning and alternative data have proved particularly useful in credit screening and risk pricing, often outperforming traditional statistical models. These technologies are not merely tools for efficiency; they are reshaping the information architecture of financial markets.
Within Islamic finance, a growing body of research addresses the convergence of technology and Shari’a-compliant systems. Both the Accounting and Auditing Organization for Islamic Financial Institutions (AAOIFI) and the Islamic Financial Services Board (IFSB) have issued guidance on digital transformation, emphasising Shari’a governance in FinTech applications. Industry reports document digital sukuk, AI-driven takaful models, and
Blockchain-based waqf platforms, all of which are positioned to improve financial inclusion while ensuring compliance. Scholars nonetheless caution that new technology must not be used in ways that infringe the Islamic prohibitions on riba, gharar, and maysir. A contemporary understanding of maqasid al-Shari’a — the higher objectives of Islamic law — is central to this analysis. Scholars such as Jasser Auda (2008) advocate a holistic, systems-based approach that emphasises human well-being, equity, and development rather than literalism. This orientation closely parallels socially responsible finance, which seeks to ensure that financial activity advances social justice, environmental sustainability, and poverty alleviation. Maqasid thus provides an ethical framework for assessing whether new technologies serve the preservation of faith (deen), life (nafs), intellect (aql), lineage (nasl), and wealth (maal) in an AI-FinTech context. The literature offers both encouraging and cautionary signals. While AI holds great promise for serving the public good (maslaha), obstacles remain, including algorithmic bias, data exploitation, and regulatory arbitrage. This chapter examines how Next-Gen AI-powered FinTech can, if properly governed, drive a transformation of financial intermediation in the service of the maqasid.
Technological Transformation of Financial Intermediation
The convergence of Next-Generation Artificial Intelligence (NGAI) and FinTech is driving a paradigm shift in financial intermediation, from traditional centralised structures toward more dynamic, technology-driven solutions.
Traditional financial intermediation operates through a centralised set-up in which intermediaries undertake delegated monitoring, liquidity provision, and risk transformation (Diamond, 1984). By contrast, AI-based models harness large volumes of data and computational power to automate and optimise these functions. The key differences are summarised in Table 11.1. This transformation is powered by several key technologies:
Blockchain and smart contracts provide transparent, tamper-resistant records and can automatically execute contractual terms without intermediaries. In Islamic finance, smart contracts can be programmed to fulfil Shari’a requirements, such as prohibiting riba and enforcing risk-sharing arrangements.
Decentralised Finance (DeFi) represents the most extreme form of disintermediation. Built on Blockchain, DeFi platforms enable lending, borrowing, and trading without traditional institutions. Alongside greater transparency and accessibility, however, DeFi introduces new systemic risks such as smart-contract vulnerabilities and liquidity fragmentation.
Robo-advisors use AI-powered algorithms to deliver automated investment advice and portfolio management. By analysing investor profiles, risk appetite, and market conditions in real time, they provide low-cost solutions that are especially attractive to retail and SME investors in emerging markets.
Table 11.1: Traditional vs. AI-Driven Financial Intermediation
Aspect
Traditional Model
AI-Driven FinTech Model
Structure
Centralised, hierarchical
Decentralised / hybrid networks
Decision-making
Manual, relationship-based
Real-time, data-driven, algorithmic
Data sources
Historical financial data
Alternative + unstructured big data
Transaction speed
Days (settlement delays)
Seconds to instantaneous
Cost structure
High overhead (branches, staff)
Significantly lower marginal costs
Risk assessment
Static credit scoring
Dynamic, predictive AI models
Customer access
Limited by geography & documentation
Borderless, inclusive (thin-file borrowers)
Governance
Regulatory compliance & human oversight
Algorithmic + smart-contract automation
Source: Adapted from Aldasoro et al. (2025) and Philippon (2016).
Peer-to-peer (P2P) lending platforms connect borrowers and lenders directly through advanced AI matching engines. Non-traditional information, such as mobile usage, behavioural signals, and transaction patterns can be used to assess creditworthiness, which is a key factor in extending finance to previously unbanked populations.
AI credit scoring is among the most transformative applications. Unlike traditional FICO-style models, AI systems analyse large and varied datasets to build dynamic risk profiles. Research suggests such models can materially reduce default-prediction errors while expanding credit access.
Disintermediation and New Forms of Reintermediation
The first wave of FinTech was marked by disintermediation, which is the partial or complete removal of traditional intermediaries. Yet a process of reintermediation is also under way, as new technology-led entities, such as BigTech, FinTech platforms, and specialised AI providers step into intermediary roles. This is giving rise to hybrid models in which incumbent banks partner with or acquire FinTech firms to remain relevant, a “platformisation” of finance. In the Islamic finance context, this transformation offers distinctive opportunities. Institutions can use these technologies to design more authentic risk-sharing products, strengthen Shari’a governance by automating screening, and extend outreach to under-served Muslim communities worldwide. With the pace of change, however, come pressing questions of regulatory oversight, consumer protection, and the maintenance of ethical standards. The technological shift is not merely about efficiency. It represents a paradigm change in how value is created, how risk is managed, and how trust is established in financial systems. The following sections examine these implications through the lenses of efficiency, security, and maqasid al-Shari’a.
Profit-and-loss-sharing structures that require continuous supervision, such as mudaraba and musharaka contracts, can be monitored using AI-powered dashboards, reducing agency costs and improving transparency
Efficiency Gains and Operational Revolution
The introduction of Next-Gen AI into FinTech is generating unparalleled efficiency, reshaping the operating environment of financial intermediation. These gains manifest in cost reduction, speed, scalability, and inclusiveness, offering Islamic financial institutions a strong platform to become more competitive and impactful.
Cost and Real-Time Asset Allocation
Traditional financial institutions are frequently burdened by long settlement cycles and high branch, manual-processing, and compliance costs. AI-powered systems, by contrast, support real-time asset allocation and portfolio optimisation. Machine-learning algorithms continuously analyse market conditions, liquidity positions, and risk factors, and can rebalance assets instantaneously.
Industry studies suggest that intelligent automation across loan processing, compliance monitoring, and customer service can reduce operational expenses substantially relative to traditional
methods. For Islamic finance, and especially for profit-and-loss-sharing structures that require continuous supervision, such as mudaraba and musharaka contracts, can be monitored using AI-powered dashboards, reducing agency costs and improving transparency.
Alternative Data and Financial Inclusion
The use of alternative data sources beyond traditional banking records is among the most transformative features of AI-FinTech. Mobile-phone usage, utility payments, e-commerce behaviour, satellite imagery, and psychometric data can help build accurate profiles of individuals and SMEs excluded from formal finance.
This capability speaks directly to the Islamic finance goal of financial inclusion. In many OIC countries, large segments of the population lack formal credit histories and remain unbanked. Evidence suggests AI models can expand the effective credit market for thin-file borrowers while improving the accuracy of default prediction. Such developments align with the objective of preserving and growing wealth (hifz al-maal) for individuals and communities alike.
Personalised Islamic Financial Products
AI enables the hyper-personalisation of Shari’a-compliant products. Robo-advisors and generative-AI systems can design bespoke solutions based on individual risk profiles, cash-flow patterns, and ethical preferences. Examples include:
AI-based Sukuk Structuring: Algorithms that optimise asset selection, pricing, and tranching while ensuring full Shari’a compliance.
Intelligent Takaful Models: Dynamic contribution and claim adjustment based on real-time health and behavioural data.
Personalised Mudaraba Investments: Platforms that match investors with ethical projects using predictive analytics on venture success. These innovations move Islamic finance from standardised, one-size-fits-all offerings toward customer-centric solutions that better serve diverse needs.
Machine-learning models are considerably better than rule based systems at recognising unusual transaction behaviour, sophisticated fraud schemes, and potential money-laundering activity
Operational Efficiency in Islamic Banks: Illustrative Examples
A number of Islamic banks are already realising substantial benefits. CIMB Islamic Bank (Malaysia) and Al Rajhi Bank (Saudi Arabia) have applied AI to accelerate credit decisioning and customer onboarding, with the former reporting loan processing up to 70 per
cent faster. Dubai Islamic Bank has deployed AI-driven anti-money-laundering (AML) solutions that reduced false-positive rates by more than 50 per cent, freeing compliance teams in the UAE to focus on higher-value activities. Bank Syariah Indonesia (BSI) has integrated AI chatbots and predictive analytics to improve customer engagement and reduce operational costs. These examples show that AI adoption in Islamic banking can deliver both cost savings and a competitive edge relative to conventional banks and conventional FinTech offerings.
Security,RiskManagementandEthicalChallenges
Next-Generation AI in FinTech delivers significant efficiency benefits, but it also raises a distinct set of security, risk, and ethical issues that must be addressed, especially within the Islamic finance context.
Proactive Fraud Detection and Cyber Resilience
AI systems can markedly improve security by enabling continuous, real-time threat monitoring. Machine-learning models are considerably better than rule-based systems at recognising unusual transaction behaviour, sophisticated fraud schemes, and potential money-laundering activity. By analysing thousands of parameters in real time, advanced AI has helped some institutions reduce fraud losses substantially. In terms of cyber resilience, AI-driven systems provide real-time threat intelligence and automated response, strengthening protection against the evolving threats that target financial infrastructure.
Table 11.2: Efficiencies in Banking Operations with AI Integration
Institution
Module/Component
Benefits
CIMB Islamic Bank (Malaysia)
Credit Decisioning and Customer Onboarding
Loan processing up to 70 per cent faster
Al Rajhi Bank (Saudi Arabia)
Credit Decisioning and Customer Onboarding
--
Dubai Islamic Bank
AI-driven Anti-Money-Laundering (AML)
Reduction in false-positive rates by more than 50 per cent
Bank Syariah Indonesia (BSI)
Customer Engagement
AI Chatbots, Predictive Analytics
Reduction in operational costs
Algorithmic Bias, Adversarial Attacks, and Data Privacy
These benefits are accompanied by new vulnerabilities. A major concern is algorithmic bias, whereby AI systems trained on historical data can inadvertently perpetuate discriminatory practices, excluding some groups from financial services. Model integrity is also increasingly threatened by adversarial attacks, in which input data is manipulated to deceive AI models. Data privacy is a further challenge. Whereas frameworks such as the GDPR emphasise consent and data minimisation, Islamic finance principles add the imperative of consistency with the Shari’a values of trust (amana) and the safeguarding of information against exploitation. Reconciling data-driven innovation with the duty to protect privacy requires new governance systems that honour both regulatory obligations and Islamic ethical principles.
Shari’a-Specific Challenges: Gharar, Maysir, and Riba-Free AI Models
In an Islamic context, avoiding riba (interest), gharar (excessive uncertainty), and maysir (gambling) is paramount when deploying AI systems. Opaque, “black-box” models can give rise to gharar, since it becomes difficult to comprehend and explain the financial decisions they produce. Likewise, poorly governed generative-AI systems used in trading or investment advice can drift toward the speculative behaviour. Building a genuinely riba-free AI model requires integrating Shari’a parameters at the architectural level rather than adding them afterwards. This includes avoiding interest-based metrics as training benchmarks and preserving profit-and-loss-sharing principles in AI-derived recommendations.
Opportunities and Limitations of AI for Shari’a Compliance
On the positive side, AI provides powerful tools to strengthen Shari’a governance. Shari’a-screening algorithms can monitor vast universes of securities, commodities, and business activities in real time against ratio screens and prohibited-activity criteria. Natural language processing (NLP) can automatically analyse company reports and contracts for non-compliant elements. Several institutions have begun to combine AI with blockchain-based, immutable audit trails for takaful and waqf to improve transparency. Experts caution is needed, however, because AI cannot fully replace qualified human Shari’a scholars. While technology excels at analysing data and recognising patterns, the ultimate interpretation and issuance of fatwas must remain under the supervision of qualified human authorities.
Maqasid al-Shari’a and Social Responsibility Perspective
The integration of Next-Gen AI-driven FinTech into financial intermediation must ultimately be evaluated through the lens of maqasid al-Shari’a, that is the higher objectives of Islamic law. This section examines how these technologies can advance the five fundamental objectives while strengthening socially responsible financial intermediation.
Poorly governed generative-AI systems used in trading or investment advice can drift toward speculative
Advancing the Five Maqasid through AI-FinTech
1Hifz al-Deen (Preservation of Faith): AI can strengthen Islamic financial practice by embedding Shari’a parameters into core systems. Automated Shari’a-screening algorithms and smart contracts help keep transactions compliant, reducing human error and enhancing trust in Islamic finance.
2Hifz al-Nafs (Preservation of Life): AI-powered microinsurance (takaful) and health-financing models can deliver faster claims processing and personalised risk protection. Predictive analytics can help communities prepare for health and climate-related risks, contributing directly to human well-being.
3Hifz al-Aql (Preservation of Intellect): Financial-literacy platforms using generative AI and personalised learning can educate millions in Islamic economics. Robo-advisors can reduce emotional decision-making in investment, promoting rational and ethical financial behaviour.
4Hifz al-Nasl (Preservation of Lineage/Family): AI-powered family takaful and inheritance-management tools can ensure smooth wealth transfer across generations while maintaining Islamic inheritance rules (faraid). Financial-planning tools can support family stability and social cohesion.
5Hifz al-Maal (Preservation and Growth of Wealth): This is where AI shows the strongest potential. Real-time risk management, predictive analytics, and optimised asset allocation help protect and grow wealth more effectively than traditional methods, while inclusive credit scoring expands access to capital for productive activity.
Social Responsibility, Poverty Alleviation, and Sustainable Development
AI-FinTech aligns naturally with the Islamic principle of social responsibility (mas’uliyyah ijtima’iyyah). Advanced data analytics can identify needs with greater precision and transparency, supporting more effective distribution of zakat, sadaqa, and waqf. AI can also streamline waqf asset management so that benefits endure across generations. AI can further support sustainable development by analysing environmental-impact data, verifying green projects, and tracking carbon-reduction outcomes in Green Sukuk issuance. This convergence of Islamic finance and technology can help catalyse progress toward a low-carbon, circular economy
AI-powered systems advance equity by lowering barriers for women, SMEs, and unbanked consumers. Alternative-data models can mitigate the disadvantages of collateral-based lending, which often works against women entrepreneurs. In several OIC countries, AI-enabled platforms have meaningfully expanded SME financing and women’s participation in formal finance. This directly supports the Islamic concepts of justice and beneficence in economic life (adl and ihsan).
Critiques and Opportunities from an Islamic Economics Perspective
Some critics warn that AI-FinTech could enable new forms of exploitation through data colonialism, opaque algorithmic decision-making, and the concentration of power among technology giants. Concerns about gharar within complex AI models, and the risk that technology prioritises profit over maslaha, are legitimate. Yet these challenges also present opportunities. Islamic economics, with its emphasis on ethical constraints and the common good, is well-placed to guide responsible AI development. By prioritising human oversight, transparency, and alignment with the maqasid, the industry can offer an “ethical AI” alternative to the purely commercial logic that dominates conventional FinTech.
CaseStudies&GlobalPractices
Several countries have set examples in implementing AI-based
FinTech within Islamic finance and in pursuing responsible innovation.
Malaysia continues to lead in Islamic FinTech. Bank Negara Malaysia oversees the country’s regulatory sandbox, which has enabled a series of AI-powered experiments in recent years. CIMB Islamic and Maybank Islamic have rolled out AI credit-scoring and robo-advisory platforms that have improved operational efficiency, customer experience, and Shari’a governance. The United Arab Emirates, particularly Dubai and Abu Dhabi, has established itself as a global Islamic FinTech hub. Dubai Islamic Bank and Emirates Islamic have implemented advanced AI solutions for fraud detection and personalised banking. The UAE’s digital Islamic-finance strategy encourages blockchain-based sukuk issuance and AI-supported regulatory technology (RegTech), where initiatives such as the Dubai FinTech Hive have accelerated partnerships between established Islamic banks and start-ups. Indonesia, home to the world’s largest Muslim population, shows strong potential for financial inclusion. Bank Syariah Indonesia (BSI) has developed AI-based customer-service platforms and alternative credit-scoring models to finance SMEs, including the unbanked. FinTech firms such as Investree and ALAMI combine AI-powered matching engines with Islamic P2P lending. Saudi Arabia is accelerating under Vision 2030. Al Rajhi Bank and Alinma Bank are investing heavily in AI transformation, while the Saudi Central Bank (SAMA) plays a proactive role in promoting FinTech innovation while ensuring adherence to Shari’a law. Notable projects include AI-powered takaful platforms and Blockchain solutions for cross-border Islamic trade finance.
AI-based Islamic Robo-advisors: Wahed Invest (global) and Sarwa (UAE) provide Shari’a-compliant automated investment management, making ethical investing accessible to retail clients.
Blockchain-based Waqf Management: Initiatives in Malaysia and Singapore use Blockchain to enhance transparency and efficiency in waqf administration, ensuring perpetual benefits reach intended beneficiaries.
Prospects for Bangladesh
Bangladesh represents a significant untapped opportunity. With roughly 170 million Muslims, an expanding digital infrastructure, the Bangladesh Bank’s FinTech initiatives and the Digital Bangladesh vision providing a favourable ecosystem, the conditions are promising. Islamic banks such as Islami Bank Bangladesh PLC and EXIM Bank are well placed to apply AI to agricultural financing, SME lending, and Zakat management. Locally developed AI, tuned to Bangladeshi realities such as rural inclusion and climate-resilient financing, could position the country as a leader in socially responsible Islamic FinTech across South Asia. These global practices show that successful integration of AI with Islamic finance requires thoughtful regulation, strong collaboration between incumbents and start-ups, and firm adherence to Shari’a principles. The lessons learned can inform a model suited to Bangladesh’s own context.
While the deployment of Next-Gen AI-driven FinTech offers considerable promise, particularly for Islamic finance, several regulatory, taxation, and ethical-governance issues require a proactive response.
Regulatory Gaps and Regulatory Sandboxes
One of the biggest obstacles is that existing regulatory frameworks were designed for traditional financial models and struggle to keep pace with rapid technological innovation. Key issues include the classification of novel financial activities, questions of liability in AI-driven decision-making, and the governance of cross-border data flows. Standards for algorithmic accountability and the Shari’a governance of AI systems remain poorly defined in many jurisdictions. Regulatory sandboxes, pioneered over the past decade, have helped address this gap. Countries such as Malaysia, the UAE, and Saudi Arabia have used sandboxes to test AI-FinTech innovations in controlled environments with limited live data. These mechanisms give regulators real-world insight while offering innovators greater clarity. Sandbox outcomes do not automatically scale into full regulatory frameworks, however, and consistent Shari’a supervision across jurisdictions remains an area requiring attention.
International Tax Compliance in the Digital Economy
The borderless nature of digital financial activity makes taxation particularly complex. Traditional tax systems, anchored to geographic jurisdiction and physical presence, are ill-suited to capturing value in an age where digital platforms mediate transactions, automated smart contracts generate revenue, and decentralised
networks facilitate collaboration. Questions of nexus determination, profit allocation, and the taxation of automated transactions remain unsettled internationally.
For Islamic finance, these challenges are compounded by the need to observe Shari’a-compliant taxation principles. The OECD’s work on digital-economy taxation (Pillar One and Pillar Two) offers some guidance, but enhanced coordination is needed to prevent Islamic financial institutions from facing double taxation or regulatory arbitrage.
Ethical and Shari’a Governance Imperatives
Successful implementation of AI in Islamic finance extends beyond regulation to rigorous ethical and Shari’a governance. Specialised oversight is needed to address algorithmic bias, the opacity of “black-box” models, inequities in data privacy, and the potential misuse of technology for non-compliant activities. Scholars stress that Shari’a governance must be embedded “by design” rather than applied after the fact. Beyond technical rules, effective governance requires collaboration among Shari’a scholars, technologists, regulators, and ethicists. While bodies such as AAOIFI and IFSB continue to strengthen standards for digital financial institutions, implementation capacity varies widely across markets.
Recommendations&FutureRoadmap
The following practical recommendations are intended to help realise the full benefits of Next-Gen AI-driven FinTech in a Shari’a-compliant manner.
For Policymakers and Regulators: Establish holistic regulatory frameworks that mainstream Shari’a governance within AI and FinTech guidelines; expand regulatory sandboxes with clear pathways to full licensing; build international cooperation mechanisms for digital taxation and Shari’a compliance; and invest in capacity-building for regulators on AI and Islamic finance.
For Islamic Banks: Accelerate digital transformation through partnerships with FinTech firms; build internal AI capabilities under strong Shari’a supervision; prioritise use cases that advance financial inclusion, such as SME financing and women-centred products; and adopt ethical-AI principles of transparency, fairness, and human oversight.
For FinTech Companies: Embed Shari’a principles in product design rather than as an afterthought; partner with Islamic banks and Shari’a scholars in product development; focus on solving real socio-economic problems such as poverty alleviation, sustainable development, and rural inclusion; and implement data practices with transparency and accountability.
Future Roadmap to 2030
If technology is managed responsibly, Islamic finance assets could exceed US$10 trillion by 2030. In an optimistic scenario, the future features Shari’a-native AI platforms, tokenised sukuk and waqf, and near-frictionless Islamic financial services, with Islamic finance helping to lead global ethical-AI governance through hybrid human–AI models. A less optimistic scenario envisions slower progress, constrained by regulatory hurdles and unresolved ethical dilemmas. The outcome will depend on how industry participants
act today. Executing this roadmap will require a comprehensive approach, consisting of coordinated talent development, infrastructure investment, and knowledge-sharing across the Islamic world. Emerging economies such as Bangladesh have an opportunity to leapfrog, developing locally relevant solutions that fuse technological sophistication with Islamic ethical values.
Conclusion
Next-Generation AI-powered FinTech represents an unprecedented opportunity to realign financial intermediation with the foundational principles of Islamic finance. This chapter has shown how such technologies can significantly enhance efficiency, security, and inclusion while advancing the higher objectives of maqasid al-Shari’a. With the global Islamic finance industry approaching US$6 trillion, the central question is less about technology adoption than about ensuring that technology delivers on social and ethical goals. By proactively embracing responsible innovation, strengthening governance, and reaffirming their commitment to justice and human welfare, Islamic financial institutions can lead a new era of socially responsible financial intermediation. The future of Islamic finance in the digital era is promising. With sound judgement, a collaborative spirit, and a clear ethical compass, the industry can transform technological disruption into a powerful force for sustainable development, equitable growth, and civilisational renewal.